
The Fed should hike in October, but won’t until December.
CPI Month-Over-Month
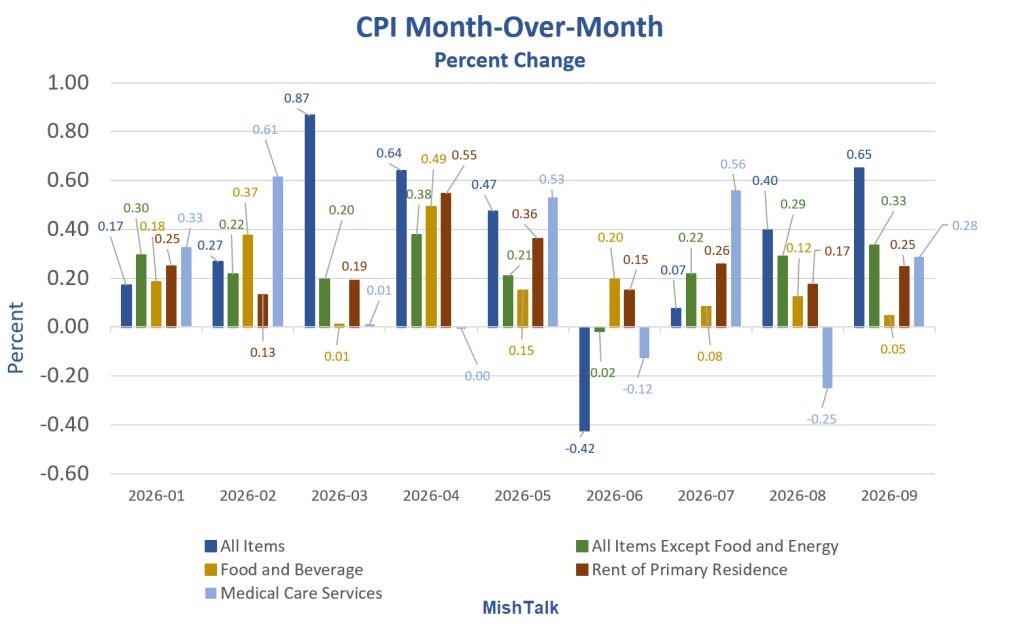
The BLS reports the Consumer Price Index for All Urban Consumers (CPI-U) increased 0.6 percent on a seasonally adjusted basis in September after rising 0.4 percent in August.
Over the last 12 months, the all items index increased 3.7 percent before seasonal adjustment.
The BLS rounds to 1 decimal point. I round to 2 decimal places
CPI Month-Over-Month
All Items: 0.65 percent
All Items Excluding Food and Energy: 0.33 percent
Food and Beverage: 0.05 percent
Shelter: 0.39 percent
Owners’ Equivalent Rent: 0.35
Rent of Primary Residence: 0.25
Medical Care Services: 0.28 percent
Medical Care Commodities: -0.66 percent
Energy: 5.20 percent
Gasoline: 9.09 percent
Food at Home: -0.07 percent
Food Away from Home: 0.23
The only bright spots, assuming you believe them, are medical care commodities and food at home.
CPI and Core CPI Month-Over-Month
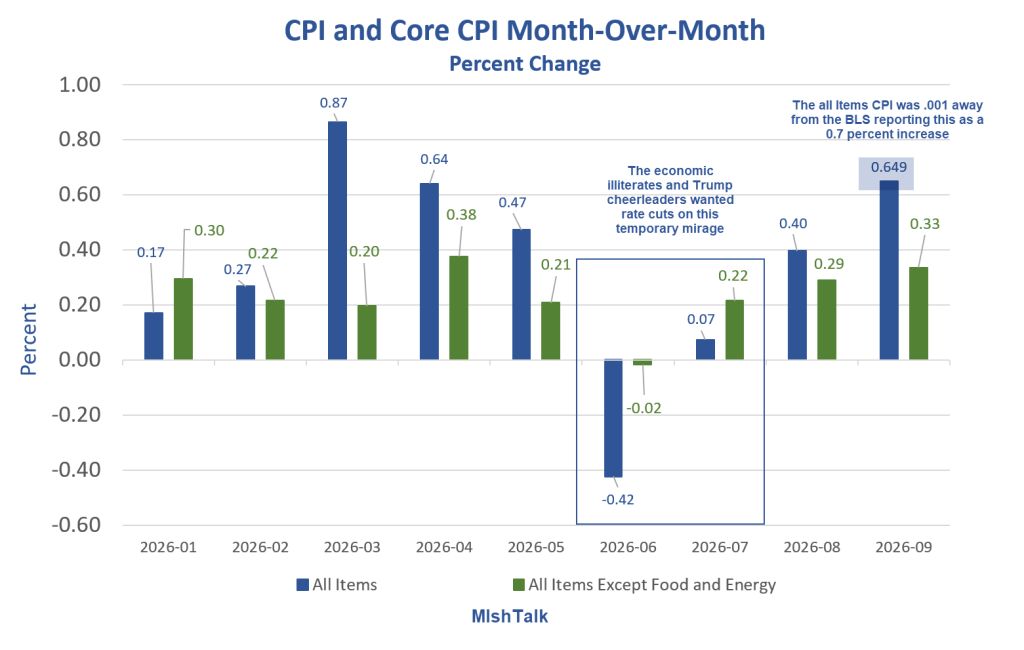
The BLS was .001 away from reporting headline CPI at 0.7 percent instead of 0.6 percent.
I calculate to two decimal places as 0.65 percent,
CPI Month-Over-Month Energy, Gasoline, Utilities
Month-Over-Month CPI: Energy, Gasoline, Utilities
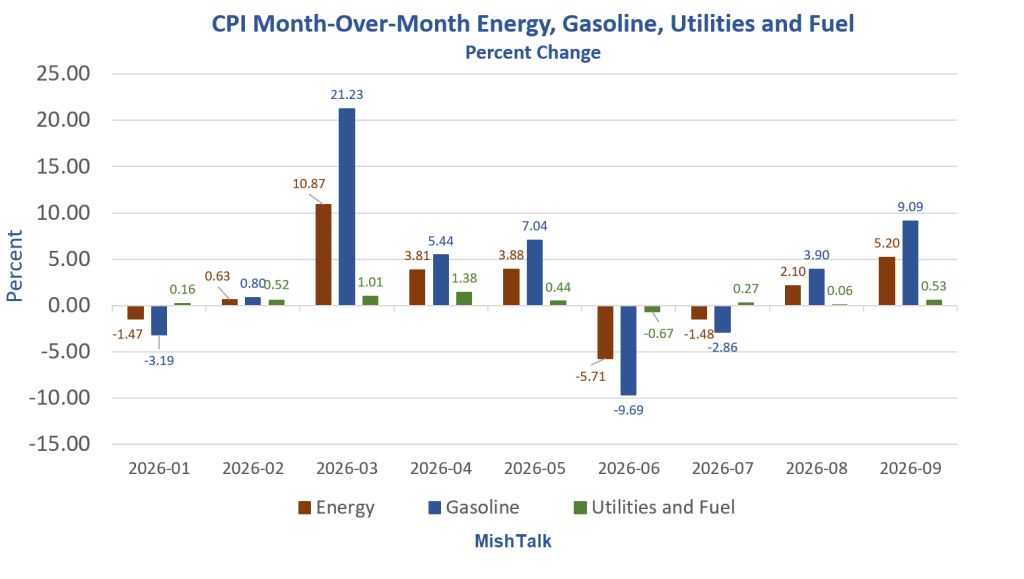
Energy, Gasoline, Utilities and Fuel Month-Over-Month
Energy: 5.20 percent
Gasoline: 9.09 percent
Utilities and Fuel: 0.53
Last month I said “Looking ahead, Trump’s moves in the strait will cause gasoline prices to jump again in September.”
Here we are.
CPI Month-Over-Month Food
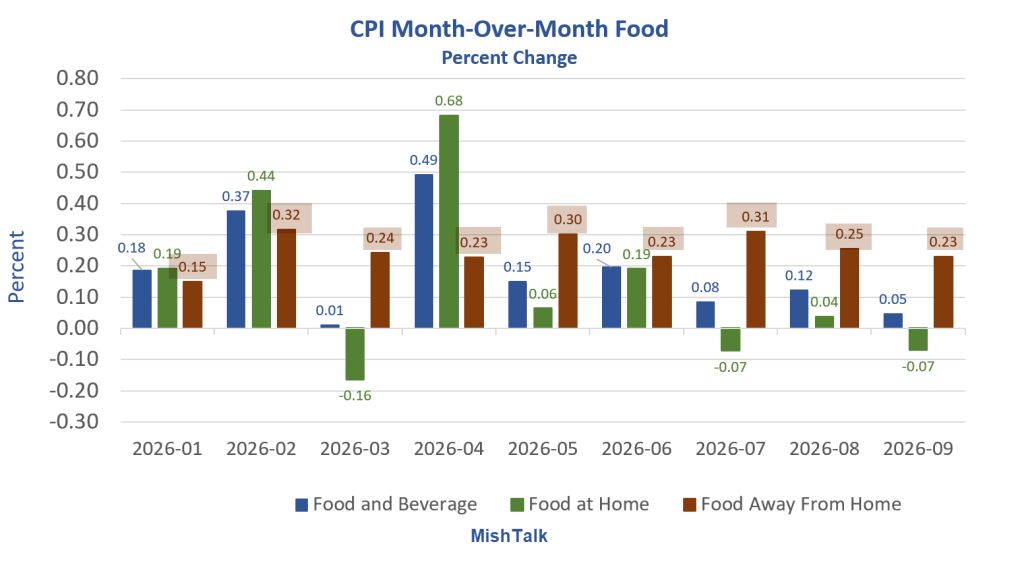
Month-Over-Month Food
Food and Beverage: 0.05 percent
Food at Home: 0.07 percent
Food Away from Home: 0.23 percent
The BLS weights food at home as 8.23 percent of the CPI. It weights food away from home at 5.29 percent of the CPI.
Actual spending is reversed. Thus, the food and beverage percent is much higher every month than reported.
CPI Month-Over-Month Shelter
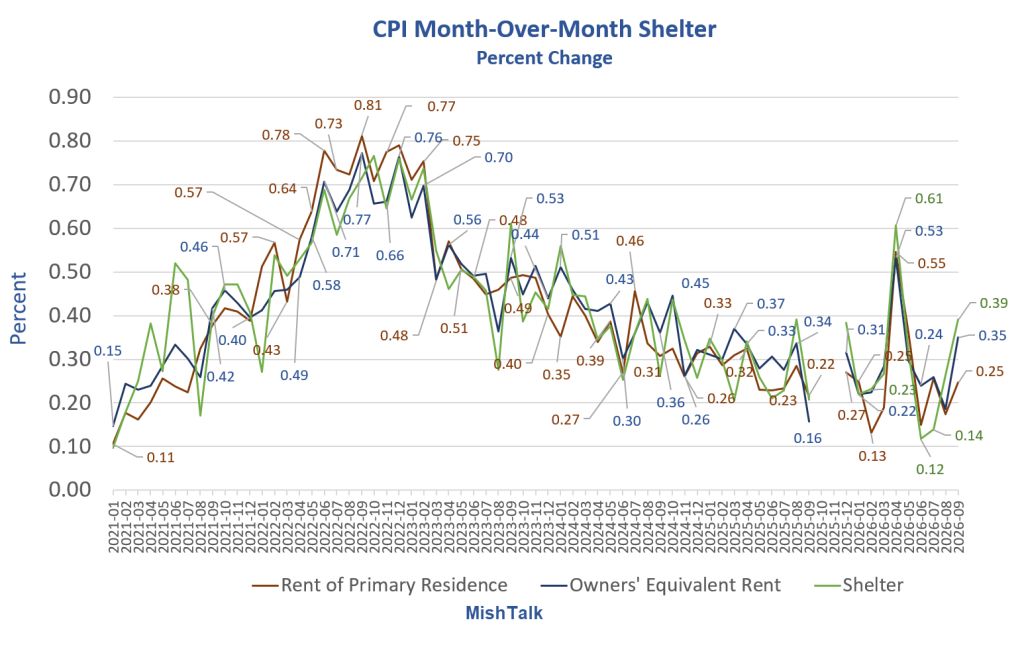
Shelter is over 35 percent of the CPI. If shelter has bottomed, and I believe so, it will add upward pressure on the CPI.
CPI, Shelter, and PCE Year-Over-Year
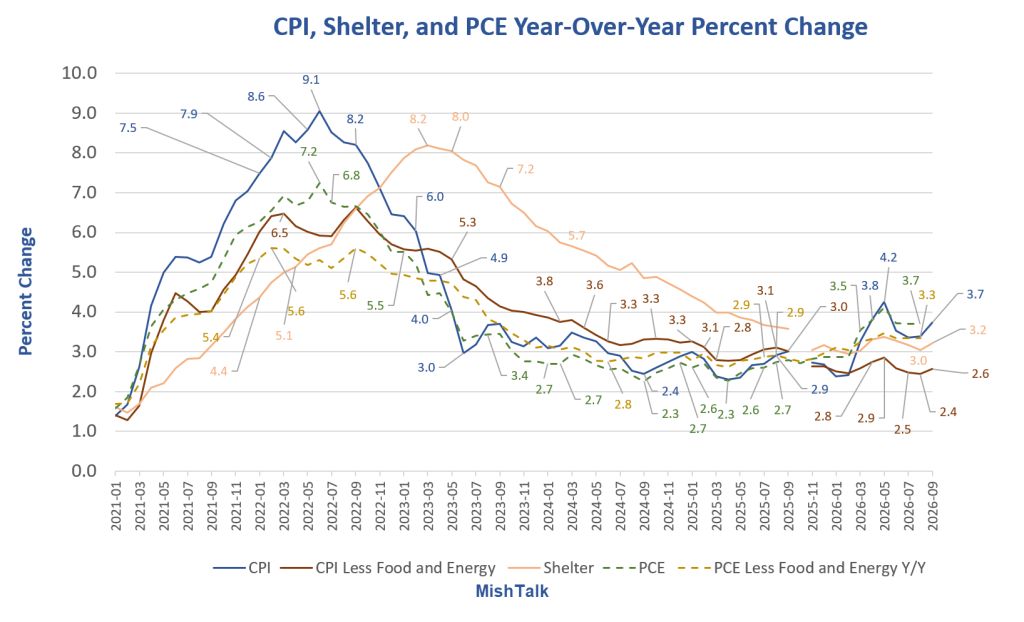
Year-Over-Year CPI and PCE Percent Change
CPI: 3.7 percent
CPI Shelter: 3.2 percent
CPI Excluding Food and Energy: 2.6 percent
PCE: 3.7 Percent (August)
PCE Excluding Food and Energy: 3.3 Percent (August)
CPI Year-Over-Year Food
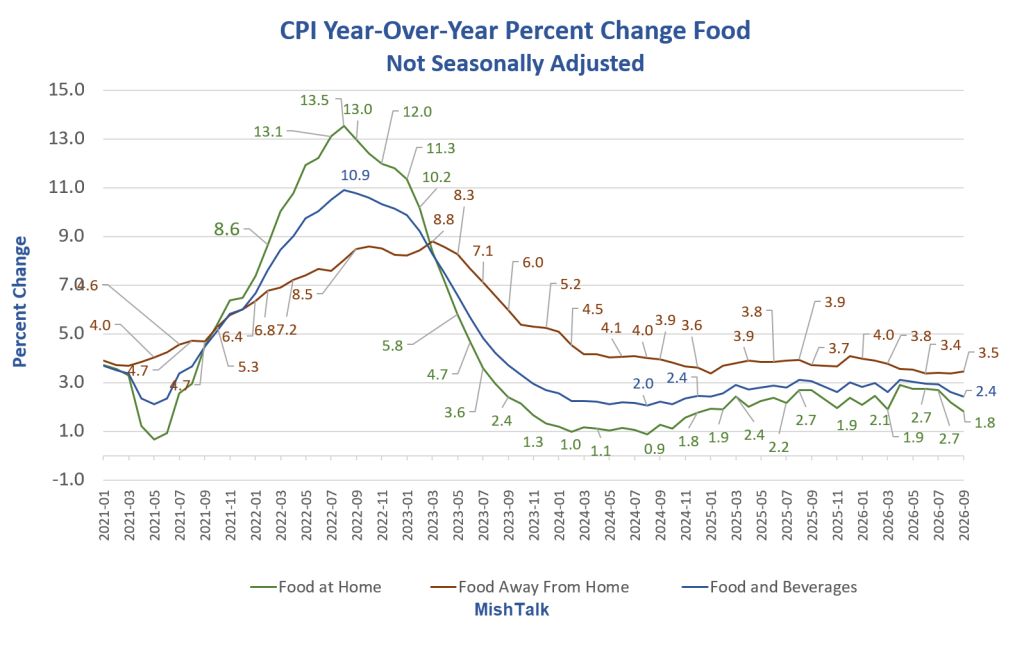
CPI Food Year-Over-Year Percent Change
CPI Year-Over-Year Food Details
Food and Beverage: 2.4 percent
At Home: 1.8 percent
Away from Home: 3.5 percent
Because the BLS underweights food at home and does not include tips, food and beverage at 2.4 percent is understated.
CPI Core Services vs PCE Less Food and Energy
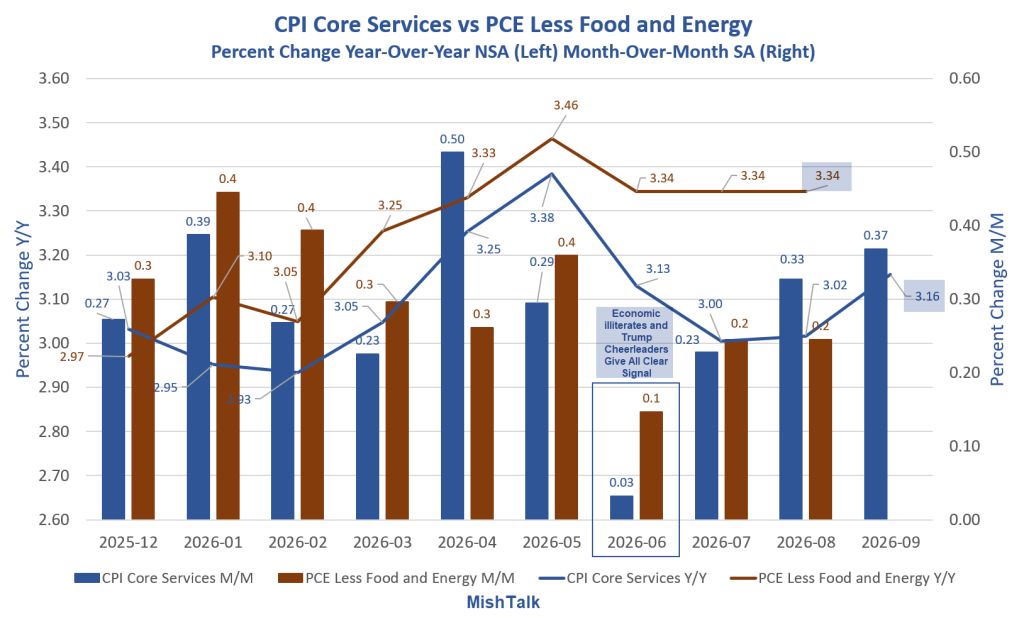
Core Services M/M and Y/Y
CPI Core Services M/M: 0.37 percent
CPI Core Services Y/M: 3.16 percent
PCE Services Less Food and Energy M/M: 0.20 percent (August)
PCE Services Less Food and Energy Y/Y: 3.34 percent (August)
This is the key chart in this post because the Fed’s preferred measure of inflation is PCE excluding food and energy.
The Fed has missed inflation targets for 63 straight months on PCE and 65 straight months on the CPI.
I fail to see how anyone can get a rate cut or even a rate hold out of that chart.
CPI and PCE Are Both Understated
Neither measure counts property taxes, homeowner’s insurance, or home prices.
Food is understated because of improper weights.
Medical insurance costs are ridiculously calculated based on retained earnings, not consumer prices.
Yet, economists wonder why people are more upset about inflation than what the numbers show.
Another Fed Rate Hike Coming but Delayed
Last month I said “A rate hike in September is all but certain after this report.”
And so it was.
I also said there would not be a hike in October, but there should be. This report sealed the “should be” aspect.
However, the Fed went out of its way to issue forward guidance when a parade of Fed governors and presidents pushed back on an October rate hike, without mentioning the obvious reason.
I never expected a hike because the next meeting is October 28, just 6 days before the midterm elections.
Following the parade of Fed yaps, rate hike odds for October plunged from over 60 percent to 20 percent, now back up to 33 percent today (but headed to zero).
Fed Chair Kevin Warsh stopped forward guidance in theory, but not practice, The Fed will always find a reason to do what it wants and telegraph it, forward guidance or not.
As of now, expect a December hike. There is no November meeting,
Related Posts
October 7, 2026: Long-Term Bond Yields Surge to New 24-Year Highs
What happened to Bessent’s “I am the house” theory?
October 9, 2026: Consumer Sentiment Current Conditions Index Drop to Record Low
By political affiliation, sentiment declines the most for independents.
October 13, 2026: Existing-Home Sales Meander Nowhere for Nearly Four Years
Since December 2022 sales have gone nowhere.
Comments
Log in or sign up to join the conversation.