
Poland: Consumer demand and labour market trends in focus
August labour market data will be released on Monday. In July, wage growth was boosted by one-off payments in some sectors (energy, forestry), and we estimate that earnings growth eased in August but probably remained above 6% year-on-year, supported by the ongoing recovery in industry and a favourable calendar effect. The general downward trend in wage growth is likely to continue in the coming months, and domestic price pressures remain contained even as headline CPI rises on the back of the energy shock. The pace of the decline in enterprise sector employment was probably unchanged, remaining at 0.8% YoY.
Monday also brings August construction output data, which disappointed significantly in July, posting an annual decline, but it is possible that there were delays in reporting completed stages of ongoing projects. Therefore, we expect solid annual growth in August, supported by projects financed under the National Recovery Plan (NRP) and the overall strength of fixed investment activity in the economy (up 8.4% YoY in 2Q26). We believe that residential construction remains the only weak spot, as the overhang of unsold dwellings continues to weigh on construction activity. By contrast, civil engineering and specialised construction works were probably robust last month.
The ongoing energy crisis and slowing wage growth are weighing on consumer spending, contributing to a gradual slowdown in private consumption (to below 3% YoY in 2Q26). However, demand for durable goods remains relatively resilient. During the last two weeks of August, VAT on fuels was temporarily reduced from 23% to 8%, which probably boosted sales of petrol and diesel, as further price increases were widely expected in September. We estimate that the August reading of retail sales of goods grew by around 5% YoY.
Czech Republic: Consumer sentiment to stabilise as industry mood softens
Wednesday brings the release of September's economic sentiment and confidence indicators. Consumer confidence has likely stabilised in September, following the previous notable drop. Solid real wage growth should still be able to hold consumer mood above its long-term average, though both may come under pressure at the turn of the year due to increasing consumer prices. The mood in industry is set to have slightly weakened throughout September, as the effect of new orders inflow was likely offset by surging oil prices and uncertainty caused by the re-escalation of the Middle Eastern conflict.
CCA: Central bank of Azerbaijan likely to leave rates unchanged
The Central Bank of Azerbaijan is likely to keep the refinancing rate unchanged at 6.50% at its upcoming policy meeting next Wednesday, as current CPI remains stable at 5.6-5.8%, within the borders of the target range of 4 ± 2%. That said, given the upward trend in global and regional inflation and rates, the tone of the commentary should become increasingly risk-focused, and hawkish guidance is not excluded as a possibility.
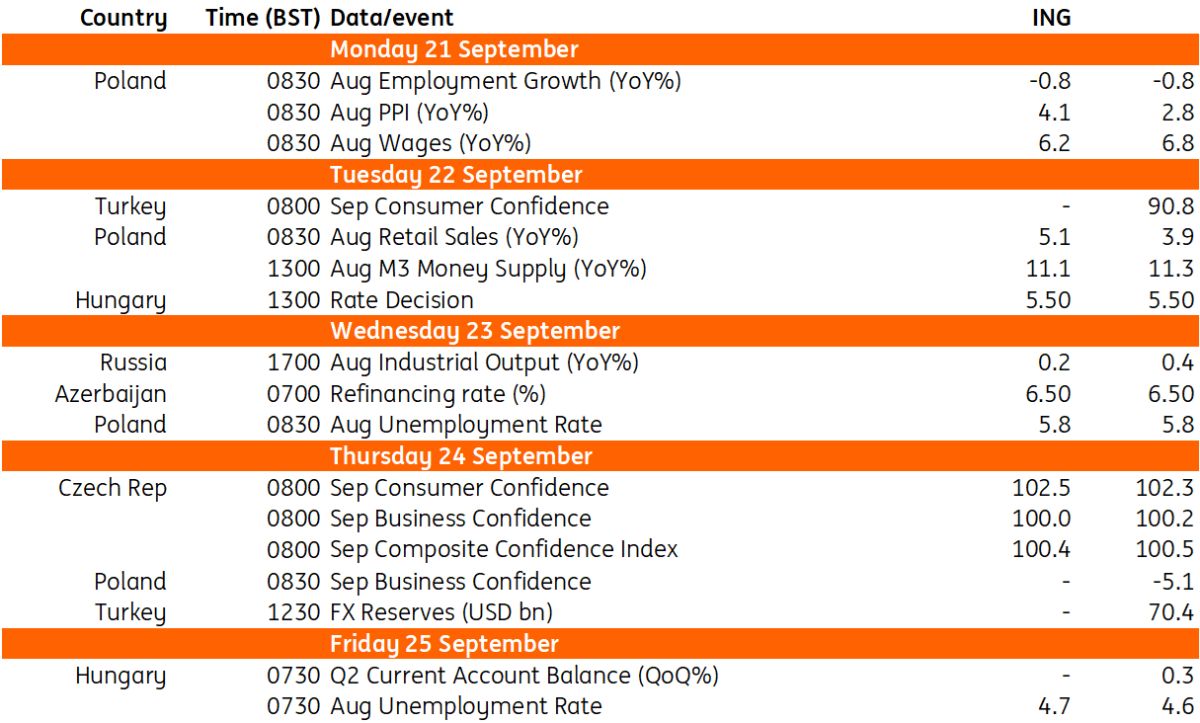
Key events in CEE & CCA next week
Comments
Log in or sign up to join the conversation.