
Hungary: Flash GDP to provide first look at third-quarter growth
Friday brings the release of the preliminary Q3 GDP estimate. We expect agriculture to have weighed heavily on growth in the third quarter, but industry – mostly driven by the new export capacities – should largely offset this. Services will remain a major positive contributor.
As this is only a flash estimate, the data will provide few details. Even so, annual growth should remain robust despite the quarterly slowdown. We therefore maintain our full-year growth forecast of 1.9% and continue to expect growth to pick up in the final quarter of the year.
Czech Republic: Confidence likely to weaken as growth softens
Monday brings the release of October confidence indicators, and on Friday we'll get the preliminary 3Q26 GDP estimate. We expect economic performance to have weakened further on an annual basis in 3Q26, but quarter-on-quarter growth should have picked up thanks to a pre-stocking effect triggered by the Hormuz conflict. Large numbers of people submitted new orders when it became clear that prices would rise and products would become more scarce.
That said, we assume this positive effect will fade at the year's turn. Both business and consumer confidence likely deteriorated in October, reflecting rising prices, the bond-market selloff, the propensity for tighter monetary policy, and the crisis in France.
CCA: Uzbekistan and Azerbaijan central banks expected to stay on hold
Wednesday brings the Central Bank of Uzbekistan's latest interest rate decision. We expect the CBRU to keep the policy rate unchanged at 14.00%, although a 50bp cut remains a close alternative. A hold appears appropriate given an increasingly pro-inflationary and hawkish global backdrop, some recent weakening in the soum and still-strong domestic demand. At the same time, the case for easing continues to build, as core inflation has recently stabilised at 5.5% YoY, not far above the 5% target, real interest rates remain high, and domestic bank funding continues to materially outperform lending growth, pointing to restrictive monetary conditions. We therefore see a hold as a tactical pause before gradual easing in the medium term.
The Central Bank of Azerbaijan announces its latest interest rate decision on Thursday. We expect the CBA to keep the refinancing rate unchanged at 6.50%, as inflation remains within the 4±2% target range. Headline CPI eased to 5.5% YoY in September, arguing against tightening. However, CPI remains relatively close to the upper end of the target range, while domestic producer-price pressures, solid credit growth and an increasingly pro-inflationary global backdrop warrant caution. We therefore retain our medium-term call for rates to remain at 6.50%, although the relatively low real policy rate leaves some risk of an upward revision to the rate trajectory should global inflation prove more persistent.
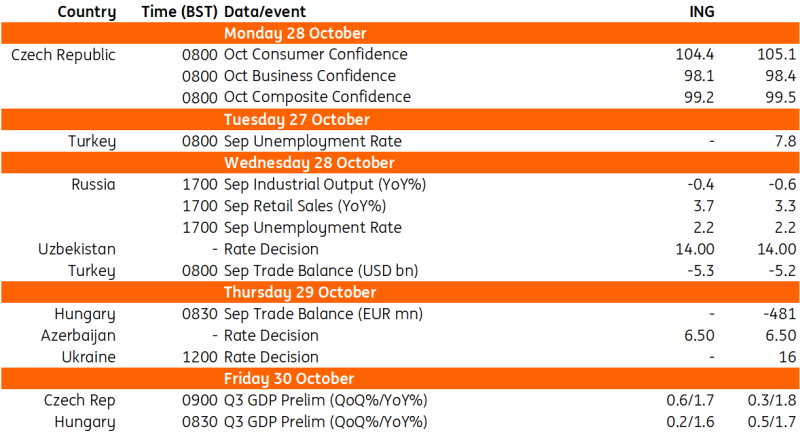
Key events in CEE & CCA next week
Comments
Log in or sign up to join the conversation.