
I’ve been writing the Safety Net column since the early days of Wealthy Retirement 14 years ago.
In all that time, I’ve yet to cover high-yielding mortgage real estate investment trust Franklin BSP Realty Trust (NYSE: FBRT). The company invests in commercial real estate debt and sports a big 12.7% yield.
We use net interest income as our measure of cash flow for mortgage REITs.
Mortgage REITs borrow money short-term and lend it out at higher rates long-term. Net interest income is the difference in the interest they pay versus the interest they make, minus expenses.
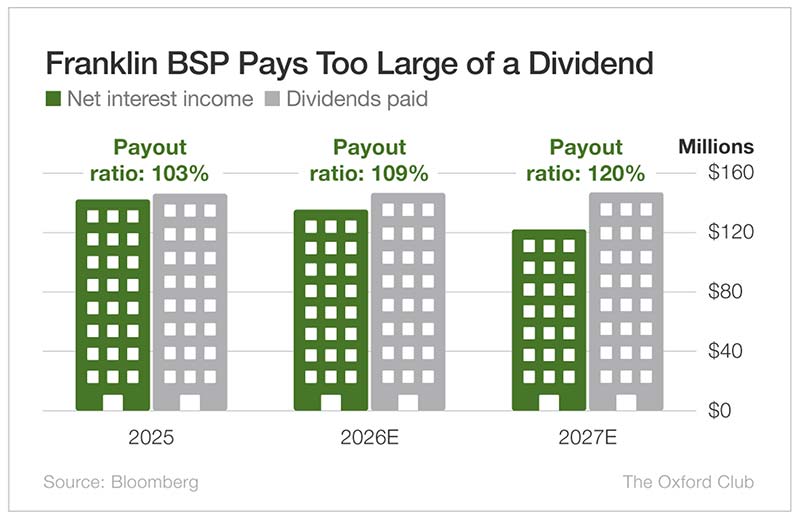
Last year, Franklin BSP generated $142 million in net interest income, a 24% drop from the previous year. Net interest income is expected to slip again to $134.6 million in 2026 and fall another 9% in 2027 to $122.3 million.
We never want to see cash flow − or, in this case, net interest income − declining.
Anytime cash flow growth is negative on a one- or three-year basis, the Safety Net model will penalize the stock.
The company paid shareholders $145.6 million in dividends last year, slightly more than it made in net interest income. The payout ratio was 103%. That means Franklin BSP paid shareholders $1.03 for every $1 in cash flow that it generated.
That’s a problem. And it gets worse.
In 2026, dividends paid are forecast to be $146.6 million for a payout ratio of 109%. In 2027, the payout ratio is projected to soar to 120%.
Payout ratios above 100% are not sustainable unless the company borrows money, sells stock, or uses cash on hand to fund the dividend.
In other words, the business is not providing all of the cash for the dividend.
It’s like having a girlfriend with expensive taste while you make minimum wage. It’s not going to end well for you.
In fact, Franklin BSP already slashed the quarterly dividend this year from $0.355 per share to $0.20, a 44% haircut.
The current $0.80 per year in dividends comes out to a too-generous 12.7% yield.
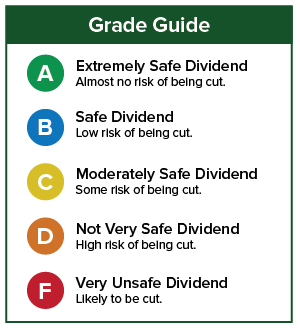
Given that net interest income is declining, the payout ratio is above 100%, and management has already shown that it will cut the dividend when necessary, Franklin BSP Realty Trust’s dividend is very unsafe.
Dividend Safety Rating: F
Comments
Log in or sign up to join the conversation.