
Booking Holdings (BKNG) stock is at 6-month lows. That may have spurred today's huge, unusual call options volume expiring in 80 days. Is BKNG stock too cheap here? There's lots of evidence that BKNG could be worth over 50% more.
BKNG is at $151.44 in midday trading. That's down from an Aug. 26 peak of $213.78. What's going on here? Earnings are due out on Nov. 3. Are investors expecting a bloodbath?
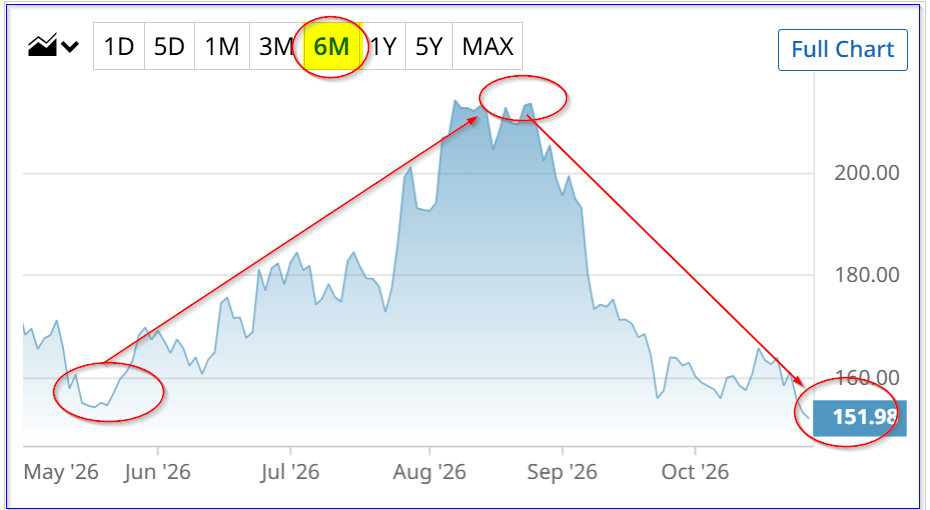
BKNG stock - last 6 months - Barchart - As of Oct. 27, 2026
Investors fear AI will take over the company's travel booking business. Meanwhile, the travel software company is generating strong free cash flow (FCF) with huge FCF margins. If the upcoming results confirm this, BKNG could be at a trough.
That may be why there is so much volume in today's call options.
Unusual BKNG Call Options Activity
This is shown in today's Barchart Unusual Stock Options Activity Report. It shows that over 21,000 call option contracts traded at the $154.00 strike price, or slightly higher (+1.69%) than today's price - i.e., essentially “at-the-market.”
Moreover, the premium paid is $11.70, so the all-in exercise cost is $165.70, or 9.4% higher. The good news is there are 80 days before expiration on Jan. 15, 2027. That's plenty of time left for this call option to work out.
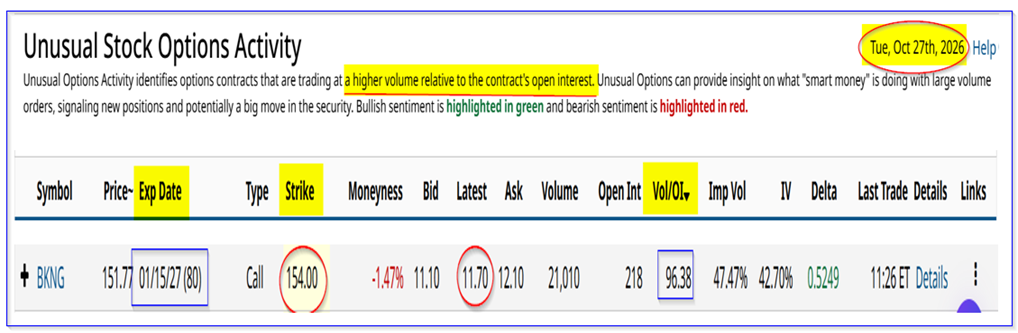
BKNG calls expiring Jan. 15, 2027 - Barchart Unusual Stock Options Activity Report - Oct. 27, 2026
And why not? Booking Holdings is generating huge FCF margins. Even if AI were to cannibalize its travel business, it would take a long time for those margins to move lower.
Moreover, analysts have higher revenue forecasts. Those two facts imply much higher FCF in the next year. Let's look at this.
Higher FCF Forecasts
Last quarter ending June 30, Booking Holdings generated $3.643 billion in FCF, representing 49.55% of revenue. In Q1, the FCF margin was 56.18%, and for the trailing 12 months (TTM), Booking Holdings generated almost $10 billion in FCF ($9.539 billion), or 33.78% of revenue (data from Stock Analysis).
Now the company makes most of its FCF during Q1 and Q2, so it's important to take a full-year view of its FCF. For example, if Booking Holdings makes a 34% FCF margin going forward, given higher revenue forecasts, its FCF will be higher.
Here's why. Analysts project revenue next year will be 9.2% higher than this year: $31.95 billion (2027) vs. $29.25 billion (2026). So, if the company makes a 34% FCF margin:
$31.95 billion x 0.34 = $10.863 billion FCF
That's over $1.3 billion higher than its Q2 TTM FCF ($9.539 billion). This could push its fair market value (FMV) much higher.
Higher Price Targets for BKNG Stock
For example, if the market eventually provides the stock with a 6.0% FCF yield (i.e., 16.67x FCF), its FMV is $181 billion:
$10.863b x 16.67 = $181 billion FMV
That is 53.7% higher than today's market cap of $117.7 billion, according to Yahoo! Finance.
That implies that the price target (PT) is 53.7% higher at $232.76 per share:
$151.44 x 1.537 = $232.76 PT
Moreover, analysts agree. Yahoo! Finance's survey of 37 analysts is $232.71, and Barchart's mean survey PT is $232.64.
Here's another way to look at its valuation. Over the past 5 years, Booking Holdings stock has had an average forward price/earnings (P/E) ratio of 28.96x (Seeking Alpha) and 18.31x (Morningstar). Let's use an average forward P/E ratio of 23.6x.
Seeking Alpha shows that for next year, earnings per share (EPS) is forecast to be $12.37. Here is the implied forward P/E valuation:
$12.37 x 23.6 = $291.93 PT
That's 93% higher than today's price. In fact, even using the 2026 EPS estimate of $10.46, the implied valuation is 63% higher:
$10.46 x 23.6 = $246.86 PT
$246.86 / $151.44 = 1.63 = 63% upside
Summary and Conclusion
So, using three models, BKNG looks undervalued: FCF model ($232.76 PT, +53.7%); Analysts' PTs ($232.71 PT, +$53.5%), and Forward P/E ($246.86 PT, +63%). On average, BKNG could be worth 56.7% more or $237 per share.
So, now wonder there is huge call option volume today for the next 80 days. At $237, the $154 call strike price, plus the $11.70 premium (i.e., $165.70), has a good expected return (ER):
$237 / $165.70 -1 = 43% ER
Even if BKNG stock produces just half that return, i.e., 21.5%, that is a good potential bet by the call option buyers. Moreover, the sellers of these calls have a good return as well:
$11.70 / $151.44 = 7.723% over 80 days, or an annualized ER of 35.2%.
The bottom line is that if Booking Holdings produces positive FCF on Nov. 3 and its TTM FCF margin is 34% or higher, BKNG could be seriously undervalued.
Comments
Log in or sign up to join the conversation.