
It’s been too long since my last article on Blackrock Silver (TSX-v: BRC) / (OTCQX: BKRRF). With shares below C$1.00, let me reiterate key investment merits. No bad news warrants the share price falling -23% in the past month. Many silver (“Ag”) juniors have been hit.

Blackrock is down ~61% from its 52-week high, yet +62% off the 52-week low. Could this be a buying opportunity? Underlying silver (“Ag”) & gold prices aren’t helping, but precious metals remain above last year’s levels. As of July 31st, there was ~C$20M in cash on the balance sheet.
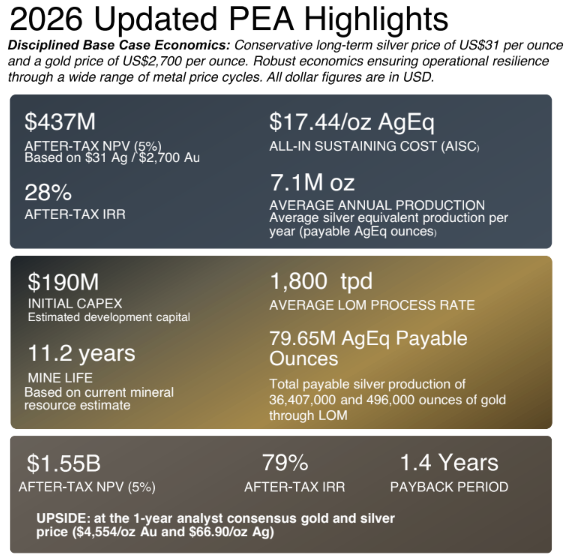
On September 23rd, management reported the first set of step-out results from its 2026 program (up to 1,100+ Ag Eq., but under 1.0 m widths). Mineralization was extended 600 meters to the NW along the Denver vein corridor at its 100%-owned Tonopah West project in Nevada.
These intercepts support the notion that high-grade mineralization extends reasonably far beyond current resource boundaries.
Some were disappointed by the narrow widths, but in my view (and management’s) hitting high grade 600 m from the delineated resource is more important than the widths. Upcoming drill results, (14 holes pending, next batch in mid-to-late October), could be impactful.
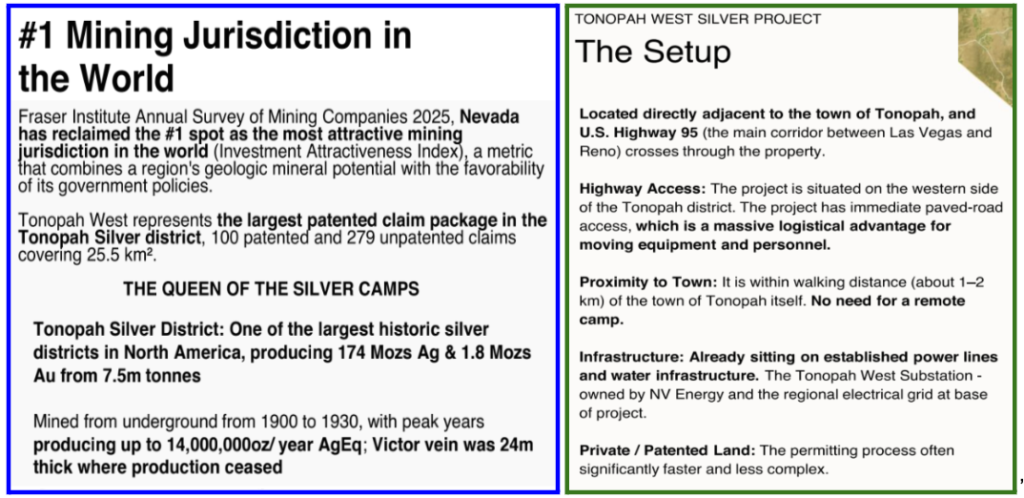
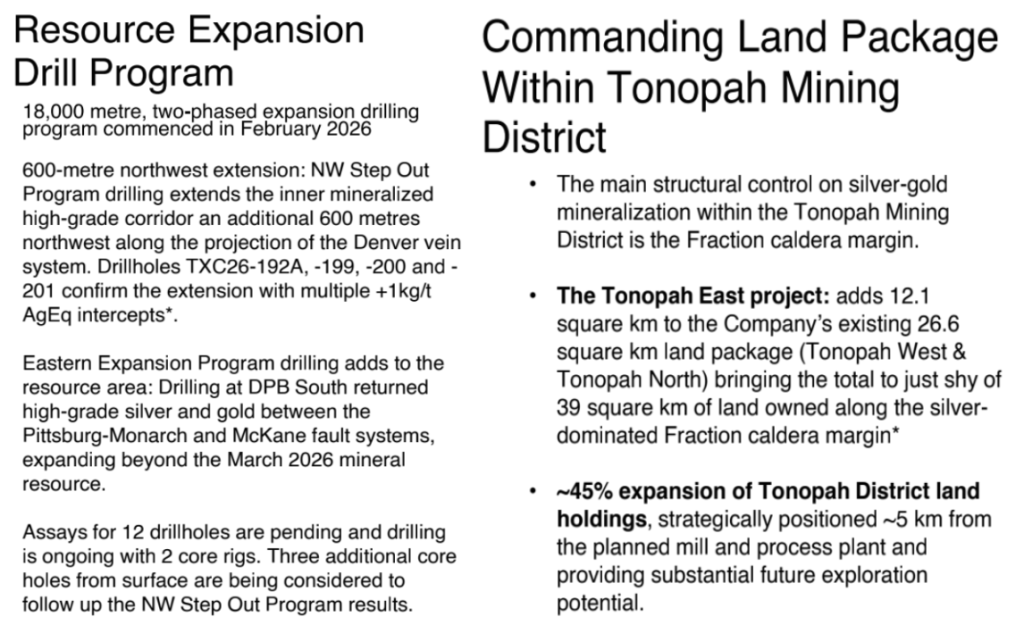
There was an important update regarding expanding the land package +45% at very low cost (less than US$50k! + a 3% NSR). It was largely ignored as the tiny purchase price implied it was no big deal.
However, based on comments made by CEO Andrew Pollard at this investment conference, there’s interest in chatroom ceo.ca about the neighbor of the newly acquired property.
Management believes Barrick Mining owns adjacent concessions, bolted directly onto the north of the newly acquired package, and has been drilling for two years.
If Barrick has been drilling for two years, does that mean it has had promising results? If promising to them, does that suggest (potentially) large-scale? Only Barrick knows… Why would the vendor sell this sizable land package so cheaply?
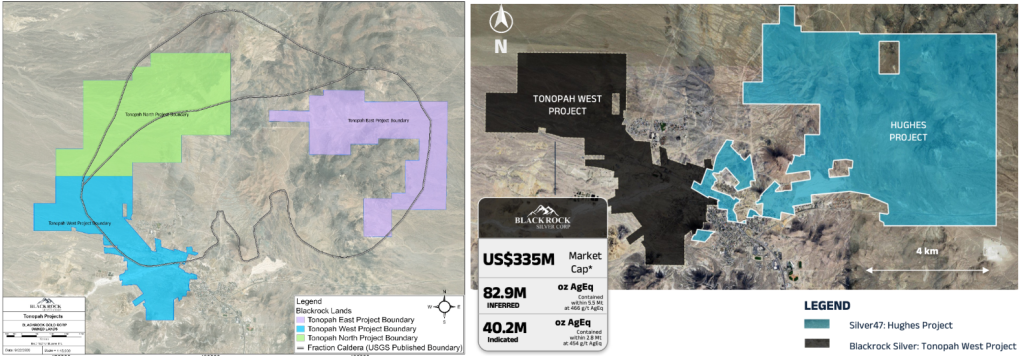
Silver47 (who’s claims border the package to the south-west, and is also currently drilling) would presumably have paid more… The seller has an existing NSR on Tonopah West. It’s selling it for nothing and taking a 3% NSR.
If the property is mineralized, Gold Royalty Corp. would benefit from its expanded NSR position as this land package is only 5 km from Blackrock’s planned mill and process plant.
Admittedly, the Barrick angle doesn’t have tangible value in and of itself — it’s smoke — not fire. Regarding Silver47, it’s merging with Bunker Hill Mining. The combined company will be larger than Blackrock.
The following intervals are the best by Silver47 on the eastern part of its Tonopah/Hughes property. Could these intervals be informative of what Blackrock’s newly acquired property hosts? I don’t know, but these holes, plus at least 7,000 m of new drilling, are only a few km away…
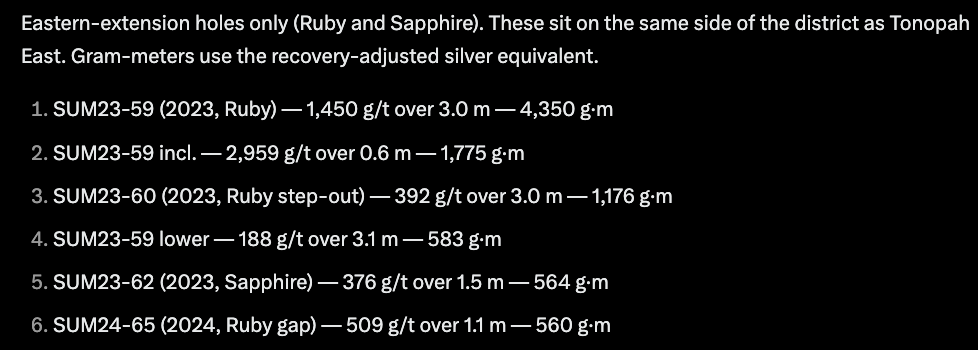
Bottom line, a meaningful amount of drilling is going on very close to Blackrock’s flagship project and newly acquired footprint.
On September 14th Blackrock announced conditional approval to graduate to the TSX main board. By doing so, it will join AG, DSV, AYA, SKE, EDR, SVM, USA, ABRA, VZLA, GGD, ASM, HSLV, NUAG, SCZ, APM, CTGO, etc.
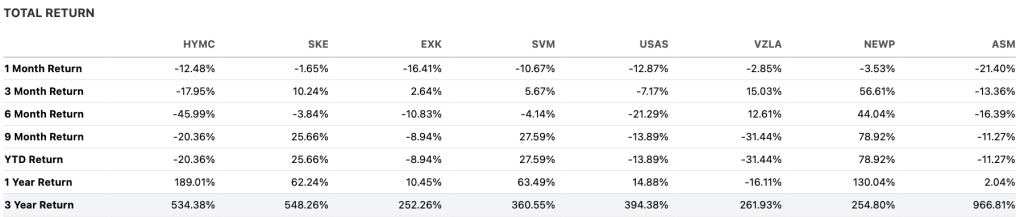
Uplifting to the main board is great, and is seen by management as a step towards a listing in the U.S. on the NYSE American or NASDAQ. Many U.S.-listed, Ag-heavy juniors trade very well (both volume & valuation). For example, the average 3-yr gains of the following dual-listed stocks is +450%…
As a reminder, Blackrock has a world-class Ag-heavy project with ~123 million Ag Eq. ounces at ~460 g/t Ag Eq. Notably, that reported grade is “block diluted.” Unlike almost every other junior, Blackrock takes into account internal dilution factors.
AI (GROK) estimates that on a non-block diluted basis, the grade is ~600 g/t Ag Eq. on the same 123M ounces. As a frame of reference, 600 g/t is ~8.8 g/t Au Eq.
Not to dwell on apples-to-apples non-diluted grade, but it’s important when comparing Blackrock to peers. In my view, Blackrock’s non-block diluted grade would be 3rd only to Alaska Silver & Sunshine Silver among dozens of Ag-heavy names I track.
The Company is rapidly advancing on obtaining key permits and is aiming to commence initial underground development by September, 2027. Going underground will allow Blackrock to convert Inferred & Indicated resources to reserves via underground drilling, and to establish portal access for test mining.
Test mining is planned to build a surface stockpile of 50,000 tonnes while providing critical data as it relates to actual mining costs, rock stability, and reconciliation against the model.
From that stockpile, 5,000 to 10,000 tonnes of ore will be handed off to Kappes, Cassiday & Associates for comprehensive metallurgical work, and run-of-mine analysis in support of plant design parameters and recovery models.
The Company is evaluating the potential to monetize the rest of the high-grade stockpile, be it through toll-milling or a raw ore off-take, as it works towards a BFS in early 2029.
Although at PEA stage, (the March PEA was an update of a prior one) Tonopah Westt is more advanced than similar stage projects due to the speed at which it’s expected to get permitted (the Project sits on private land, providing a potentially expedited path). Breaking ground next year, and test-mining in 2028.
In my view, Blackrock is a prime takeover target, but not anywhere near today’s valuation… Instead, management will continue to grow, de-risk, permit and prudently advance. Who might be interested in acquiring the Company?
Possibilities include, Barrick, Kinross (active in Nevada, but an Au focus), AngloGold Ashanti (has a major project nearby) Hecla, Coeur, First Majestic, Pan American Silver, Americas Gold & Silver, SSR Mining, Endeavour Silver, McEwen Mining, or I-80 Gold (a serial acquirer).
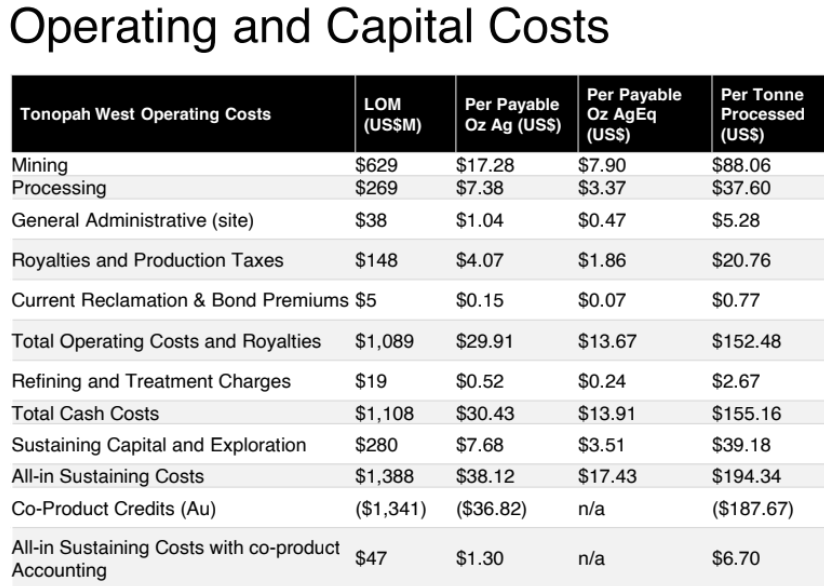
Look at the PEA economics near spot pricing… US$1.5B post-tax NPV, +79% IRR, 1.4 yr. payback period. Imagine if a larger player were to get involved to turbo-charge drilling & project development?
At full Feasibility stage, the project could have an optimized mine plan. There’s so much high-grade mineralization, the Company could mine lower grades (but more tonnage, extending mine life).
Or, if drill results are strong, management could maintain the ultra-high grade profile and STILL increase annual throughput and/or mine life. There remains significant exploration potential, especially if funded by a future strategic investor or acquirer.
Notice upfront cap-ex of just US$190M, and AISC/Ag Eq. oz. of US$17.44. The median industry-wide ASIC is fast approaching US$25/Ag Eq. — likely $25+/oz in 2H/27.
This made-in-the-USA story should be especially compelling and could attract U.S. government financial incentives like; tax breaks, low-cost loans, free-money grants, off-take agreements, or even an equity investment from the U.S. gov’t. However, to be clear, these things take time.
Blackrock Silver (TSX;V: BRC) / (OTCQX: BKRRF) is down sharply from its highs, but news flow has not been negative. Step-out drilling extended the Denver corridor a substantial 600 m, the land package grew +45% at very low upfront cost, and a TSX main board listing is imminent.
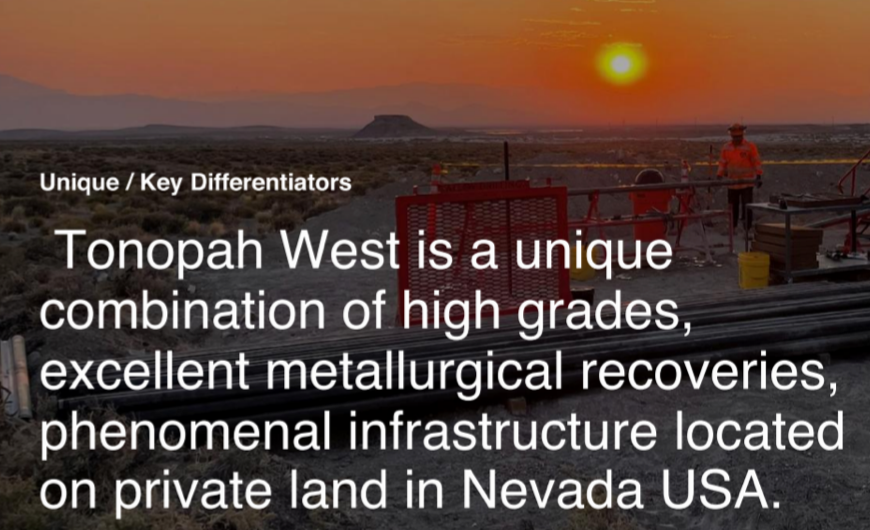
The team has drilled 18,000 m this year, with ~14 holes pending assays, and 2 core rigs still running 24/7. Moreover, drilling around Blackrock by Bunker Hill/Silver47 offers valuable information as it’s so nearby. The March PEA showed very low cap-ex & AISC/oz from an ultra high-grade Nevada project.
Underground access is targeted for 2H/2027, with the potential for test mining and modest cash flow in 2028, while management works towards a final construction decision.
Between now and a BFS, there’s ample room for more drilling and de-risking to expand mine life and improve project economics. Should this company be valued at just 15-16% its post-tax NPV(at spot prices)? Should it be 61% below its 52-week high? I don’t think so.
Disclosures/disclaimers: The content of this article is for information only. Readers fully understand and agree that nothing contained herein, written by Peter Epstein of Epstein Research [ER], (together, [ER] ) about Blackrock Silver, including but not limited to, commentary, opinions, views, assumptions, reported facts, calculations, etc. is not to be considered implicit or explicit investment advice. Nothing contained herein is a recommendation or solicitation to buy or sell any security. [ER] is not responsible under any circumstances for investment actions taken by the reader. [ER] has never been, and is not currently, a registered or licensed financial advisor or broker/dealer, investment advisor, stockbroker, trader, money manager, compliance or legal officer, and does not perform market-making activities. [ER] is not directly employed by any company, group, organization, party, or person. The shares of Blackrock Silver are highly speculative, and not suitable for all investors. Readers understand and agree that investments in small-cap stocks can result in a 100% loss of invested funds. It is assumed and agreed upon by readers that they will consult with their own licensed or registered financial advisors before making investment decisions.
At the time this article was posted, Blackrock Silver was an advertiser on [ER] and Peter Epstein owned shares in the company.
Readers understand and agree that they must conduct due diligence above and beyond reading this article. While the author believes he’s diligent in screening out companies that, for any reason whatsoever, are unattractive investment opportunities, he cannot guarantee that his efforts will (or have been) successful. [ER] is not responsible for any perceived, or actual, errors including, but not limited to, commentary, opinions, views, assumptions, reported facts & financial calculations, or for the completeness of this article or future content. [ER] is not expected or required to subsequently follow or cover events & news, or write about any particular company or topic. [ER] is not an expert in any company, industry sector, or investment topic.
Comments
Log in or sign up to join the conversation.