
The Reserve Bank of Australia is expected to hike rates by 25bp to 4.85%. Elsewhere, markets will be watching a raft of key regional data releases, including China’s PMI figures, South Korea’s trade and inflation data, Japan’s wage growth numbers and Taiwan’s latest inflation reading
Asia Research highlights of the week
RBA set to hike as inflation proves more persistent
Australia: RBA expected to hike rates by 25bp
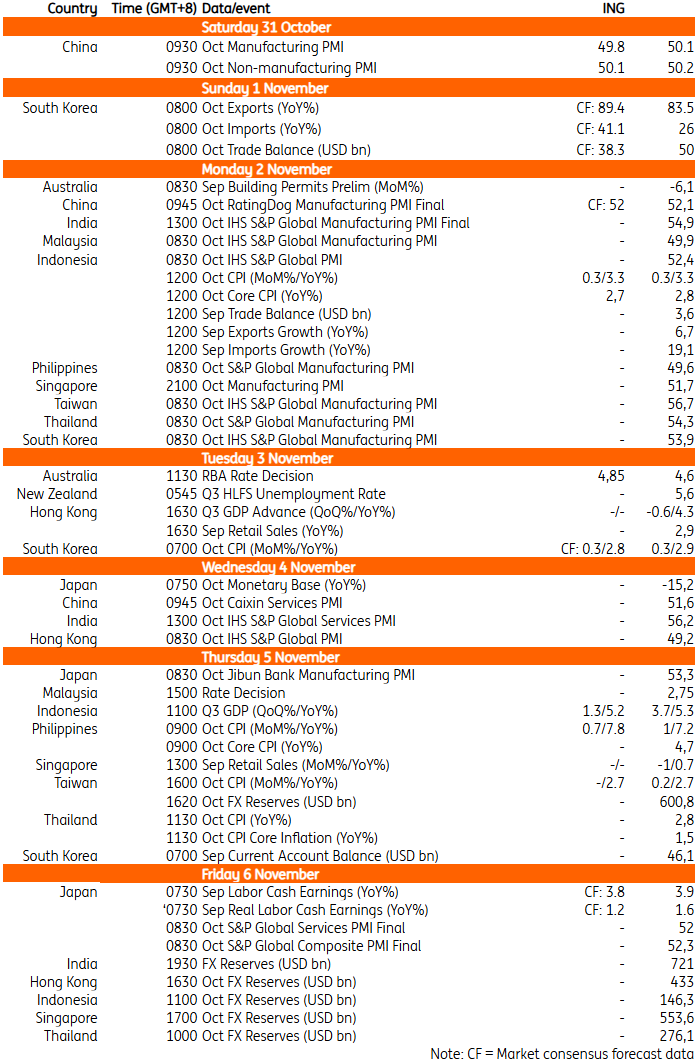
We expect the Reserve Bank of Australia to raise its policy rate by 25bp to 4.85% on Tuesday rather than wait until December. Headline inflation rose by 90bp between July and September to 4.3% year-on-year. Fuel prices largely drove the increase, while goods, services, and core inflation also picked up. With underlying inflation not yet on a sustained downward path, the case for a pause remains limited.
China: Official PMIs expected to soften slightly
China releases October purchasing managers’ index data on Saturday. We look for both manufacturing and non-manufacturing PMI data to cool slightly, down to 49.8 and 50.1, respectively. The RatingDog PMI is due on Monday. It's expected to continue outperforming other gauges, reflecting its more export-oriented respondent base. Markets are forecasting a reading of 52.0.
Taiwan: Inflation expected to remain elevated
Taiwan releases its CPI inflation data Thursday. We expect inflation to remain hot in October at around 2.7% YoY. After last month’s surprise surge, another month of high inflation would strengthen the odds for a central bank rate hike in December.
Korea: Export growth to strengthen as inflation eases
South Korea releases October trade data over the weekend. Market consensus expects export growth to accelerate to 89.4% YoY, supported by continued strength in semiconductor and AI-related demand. Imports are expected to rise to 41.1%. The trade surplus is expected to narrow to US$38.3bn from a revised US$50.0bn.
October inflation data will be released Tuesday. Market consensus expects headline CPI inflation to ease slightly to 2.8% YoY from 2.9%, while core inflation slows to 2.7% from 2.8%. Inflation would nevertheless remain above the Bank of Korea’s target. Strong exports also should continue to support growth and the case for maintaining a restrictive policy stance.
Japan: Wage growth expected to remain firm
Japan releases its September labour cash earnings data on Thursday. Market consensus expects nominal wage growth to ease slightly to 3.8% YoY from a previously revised 3.9%. Real earnings growth is seen slowing to 1.3% from a revised 1.6%. Firm wage growth should support further Bank of Japan tightening amid elevated inflation and negative real interest rates.
Key events in Asia next week
Comments
Log in or sign up to join the conversation.