
The Monetary Authority of Singapore's policy review headlines the week, with modest tightening expected alongside Singapore’s third-quarter GDP release. Markets will also focus on China’s inflation and trade data, Japan’s producer prices and machine orders, and India’s CPI inflation.
Singapore: MAS expected to tighten policy modestly
The Monetary Authority of Singapore's review will be the key event to watch. We expect a modest tightening via a 'very slight' increase in the slope of the SGD NEER policy band to around 1.5% annual appreciation, providing additional support for the Singapore dollar amid a challenging external backdrop.
Separately, GDP growth for 3Q should indicate that Singapore growth remains robust, supported by strong industrial production and electronics exports, which continue to reach new highs. Forward indicators continue to remain supportive, suggesting resilient technology demand, while stronger domestic credit growth suggests domestic demand remains strong as well.
India: Inflation set to accelerate sharply
We expect CPI inflation to accelerate sharply to 5.4%, led by food and fuel prices. More important for the policy outlook will be whether price pressures are becoming more generalised, especially as the Reserve Bank of India maintains a relatively neutral stance despite mixed guidance on the inflation outlook.
China: Inflation edges higher as trade remains strong
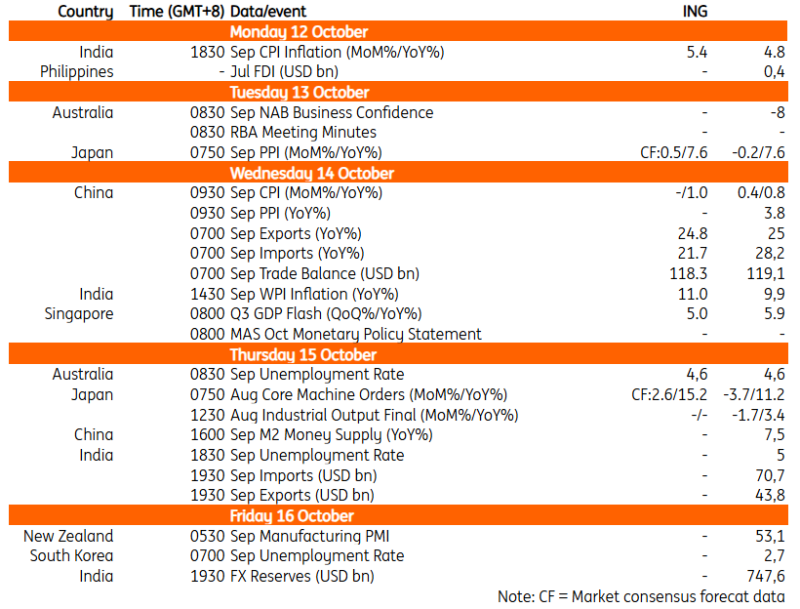
China will release its September inflation and trade data next week. We expect CPI inflation to edge up to 1.0% year-on-year, driven by higher energy prices. Trade growth is expected to remain strong, with exports rising 24.8% YoY and imports increasing 21.7% YoY, resulting in a trade surplus of US$118.3bn.
Japan: Producer prices and machine orders in focus
Japan will release its PPI data and core machine orders next week. The market expects its PPI to remain elevated at 7.6% YoY, while monthly producer prices are forecast to rise 0.5%, suggesting that upstream price pressures remain firm. Meanwhile, markets expect August core machine orders to rebound by 2.6% month-on-month, with annual growth accelerating to 15.2% YoY, pointing to continued strength in corporate capital expenditure.
Key events in Asia next week
Comments
Log in or sign up to join the conversation.