

Stocks fell today, with headlines surrounding Nvidia (NVDA) weighing on the market. The decline was relatively modest, with the S&P 500 falling just 35 basis points. For the most part, the equity market continues to churn, with money rotating between different groups of stocks. The equal-weighted S&P 500 ETF (RSP) fell 90 basis points, so the headline index could have performed much worse. However, strength in a handful of hyperscalers helped keep the cap-weighted index relatively stable.
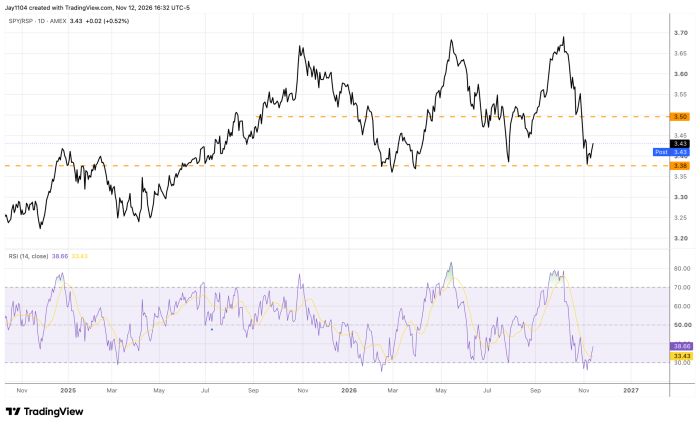
The SPY-to-RSP ratio continues to churn, but so far it has bounced off support, suggesting SPY is once again outperforming RSP. To me, that indicates mega-cap technology and AI-related stocks are leading the market again.
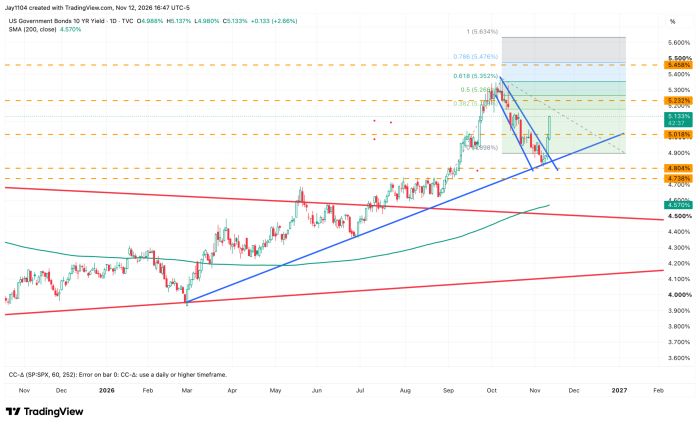
The bigger moves today were actually in the bond market, with the 10-year Treasury yield rising 13 basis points to finish the day at 5.13%. The federal budget deficit for October came in at $404 billion, which is unlikely to help matters as government debt continues to grow.
The 10-year yield is currently bouncing off an uptrend that dates back to late February and also appears to have broken out of a bull flag. Both are bullish technical developments for yields, suggesting that a move toward the 5.60% area is possible.
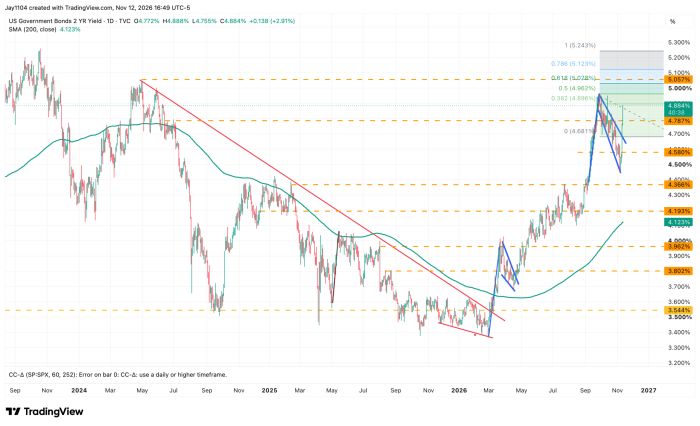
The US 2-year Treasury yield has also broken out, rising 14 basis points today to 4.89%. It appears to have broken free of either a bull flag or a falling megaphone pattern, suggesting that a move above 5% would not surprise me at all.
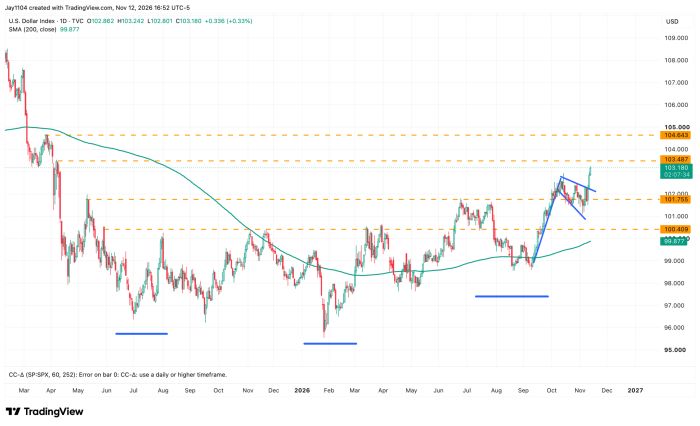
The Dollar Index is showing a similar pattern, with a breakout now taking shape. The sharp, nearly straight-line decline from April 2025 appears to be retracing, which could take the DXY back toward resistance at 103.5 and potentially as high as 104.60.
Comments
Log in or sign up to join the conversation.