
Earnings season has officially begun, and it kicked off with a bang. Alphabet reported one of the worst single-day losses in its history. I will explain exactly why, and why I added to my position when I speak about the company below. In addition to this, I added to my CPKC position on what I thought was a very solid quarter, yet a bad reaction to earnings. Again, more below.
Outside of some earnings commentary, I want to go over the Anthropic S1 and their intentions to IPO very briefly. If you are interested, there are some things you need to know.
This will be jam-packed, so let’s just get right into it.
Anthropic S1
Anthropic filed to go public on Monday. The business is, without question, exciting. However, I won’t be participating in the IPO.
I am saying this also acknowledging that I do not know if I have ever seen a company grow this fast.
There are 3 gigantic issues for me though.
The amount it has committed to spend and the structure of its current leases
The potential dilution of shareholders due to the massive amount of convertible debt it has
The way the company will be structured will leave public shareholders with very little control
First, let’s talk about the growth.
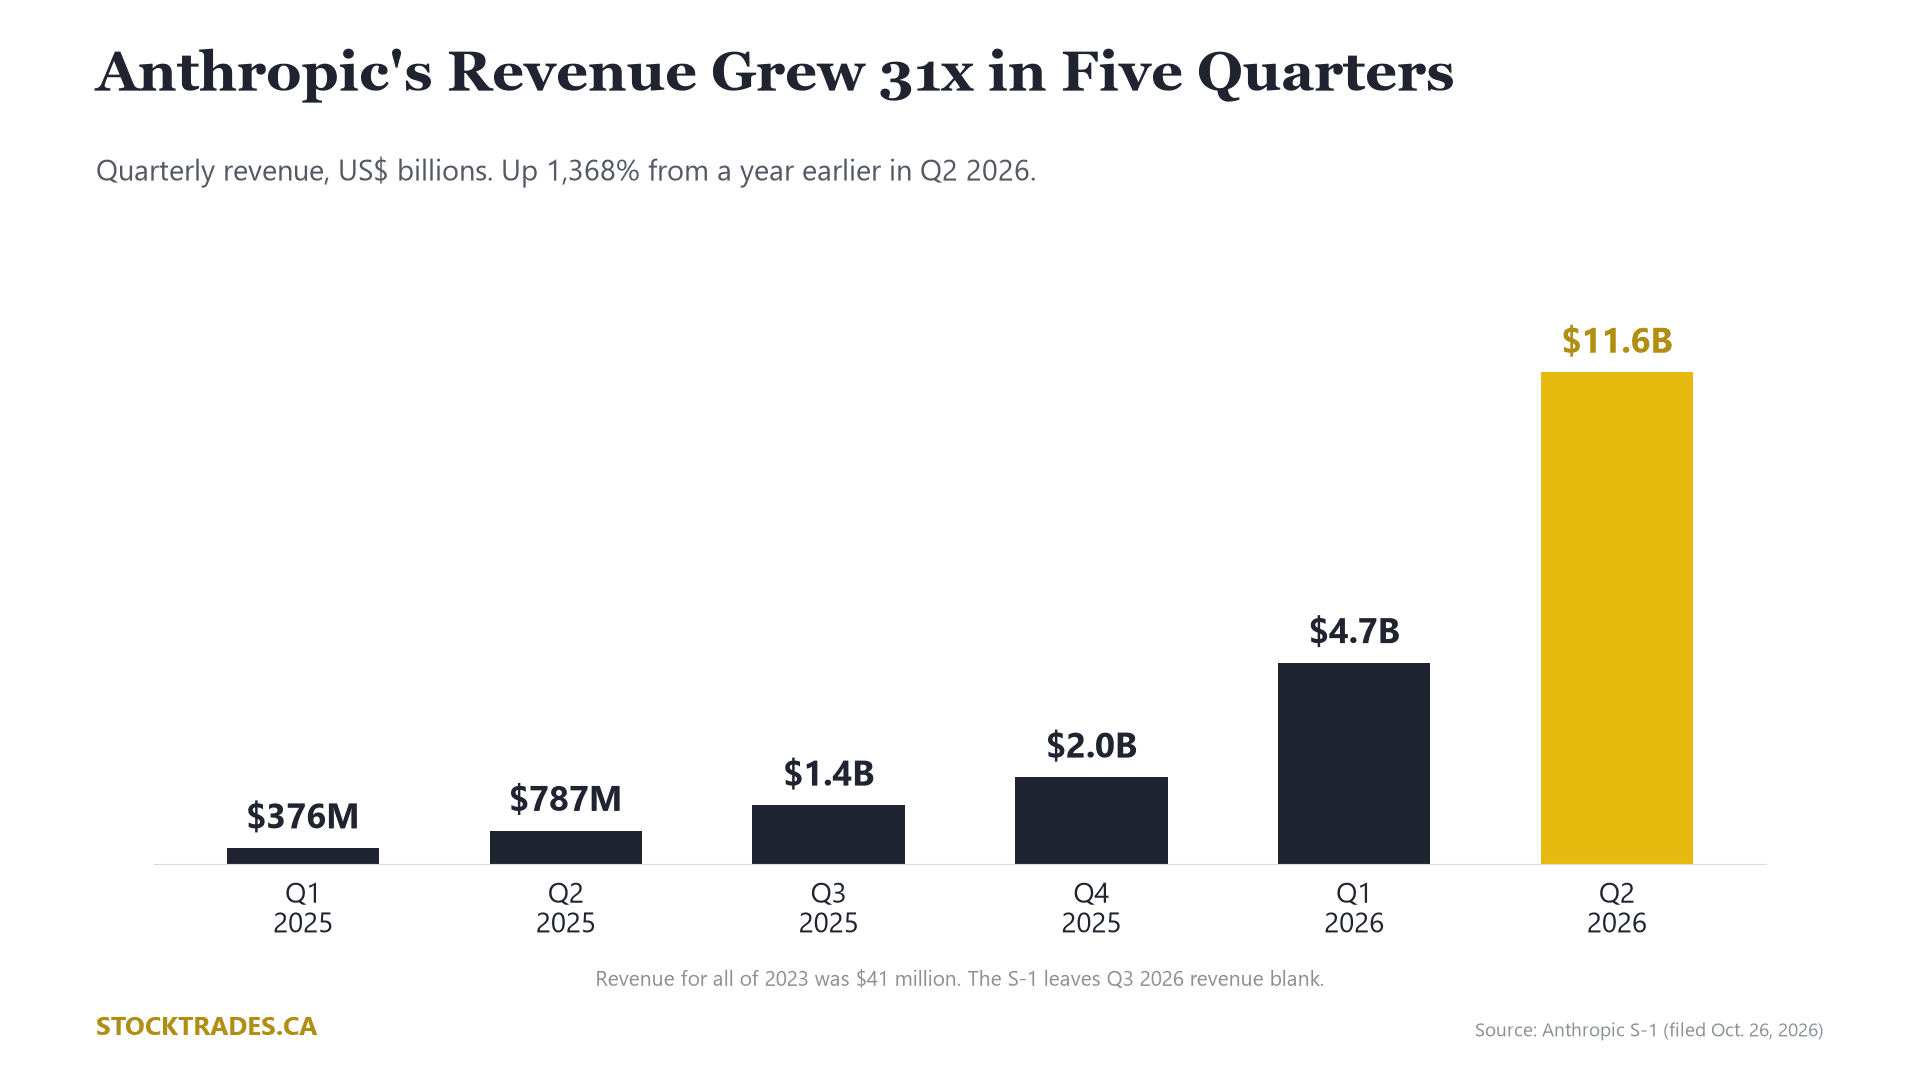
Anthropic generated $41 million in revenue during all of 2023. In the second quarter of 2026 alone, it generated $11.6 billion. That’s 282x its entire 2023 revenue, in a single quarter.
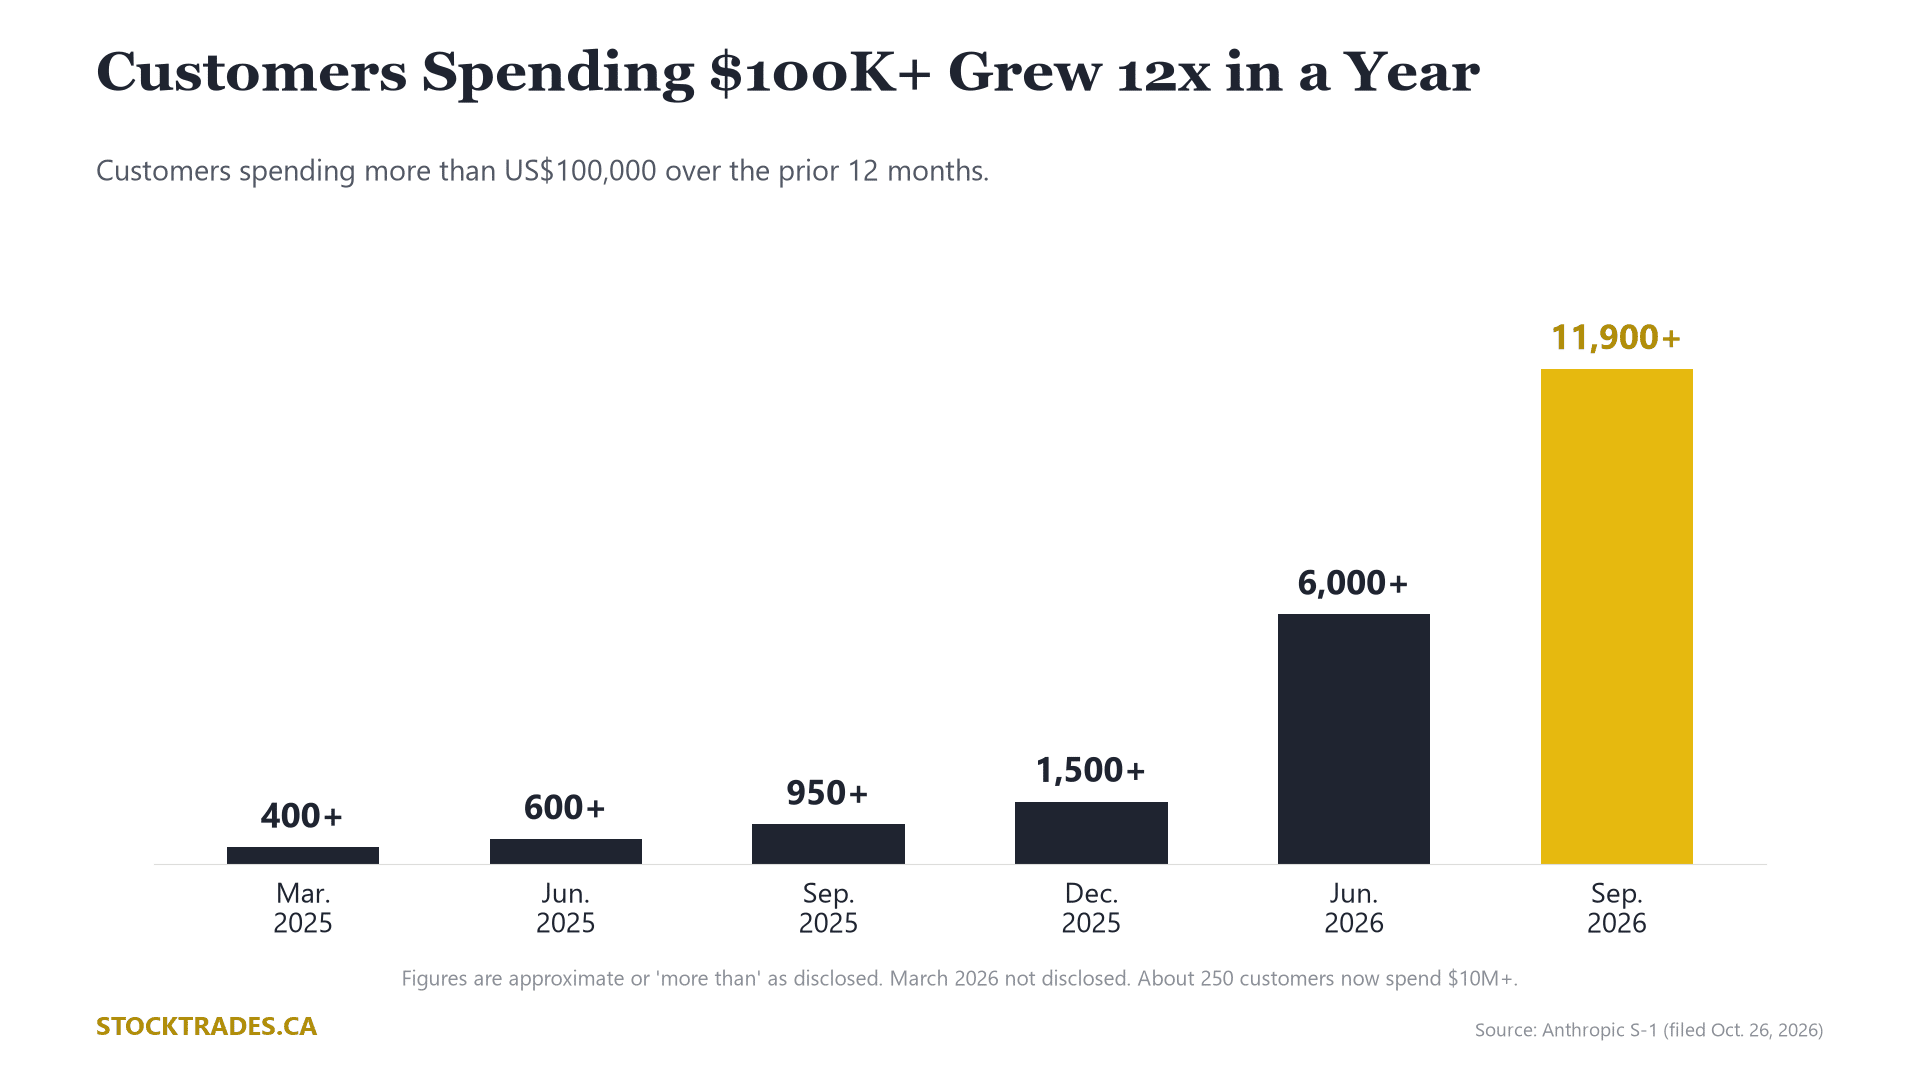
More than 11,900 customers now spend over $100,000 a year with the company. 250 spend more than $10 million annually.
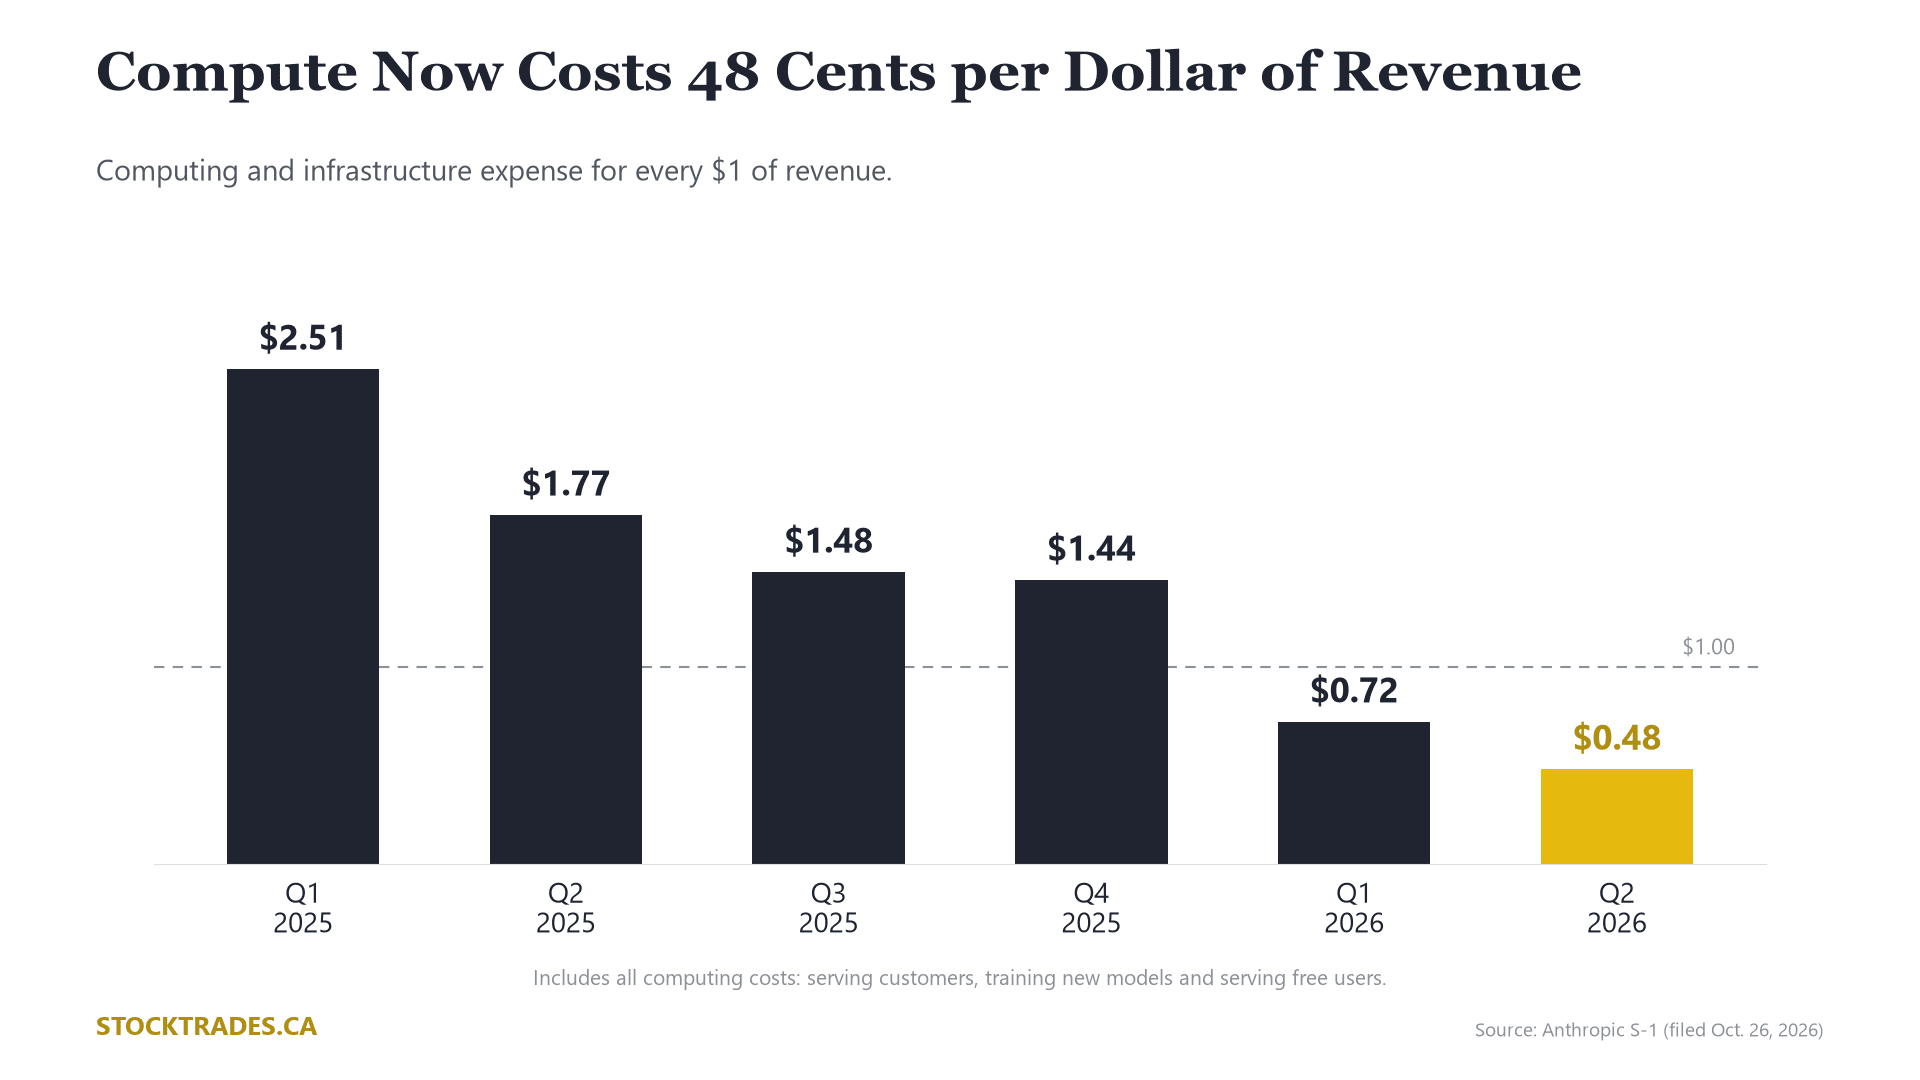
Revenue grew 1,368% year over year, while computing costs increased 300%.
That is a significant improvement. Not too long ago, for every dollar in revenue, this company was spending about $2.50 to generate it.
Here is another added difficulty, however. More than 80% of third-quarter revenue came from models released within the last 6 months. Anyone buying this company needs to ask whether or not the moat is durable long term. I sure am.
Anthropic has to keep developing products that customers want to use, or they will just be squashed by competition (GPT, Gemini, etc.) This requires constant spending.
My biggest concern is the amount Anthropic has agreed to spend
Napkin math by me, the company has committed to spending $855B on computing power and data centres. This number is hard to comprehend. This doesn’t include another $145 to $170 billion of variable commitments on top.
The company has $131.7 billion in cash and short-term investments, so it certainly isn’t short of funding today. But its contracted future revenue is only $10.8 billion.
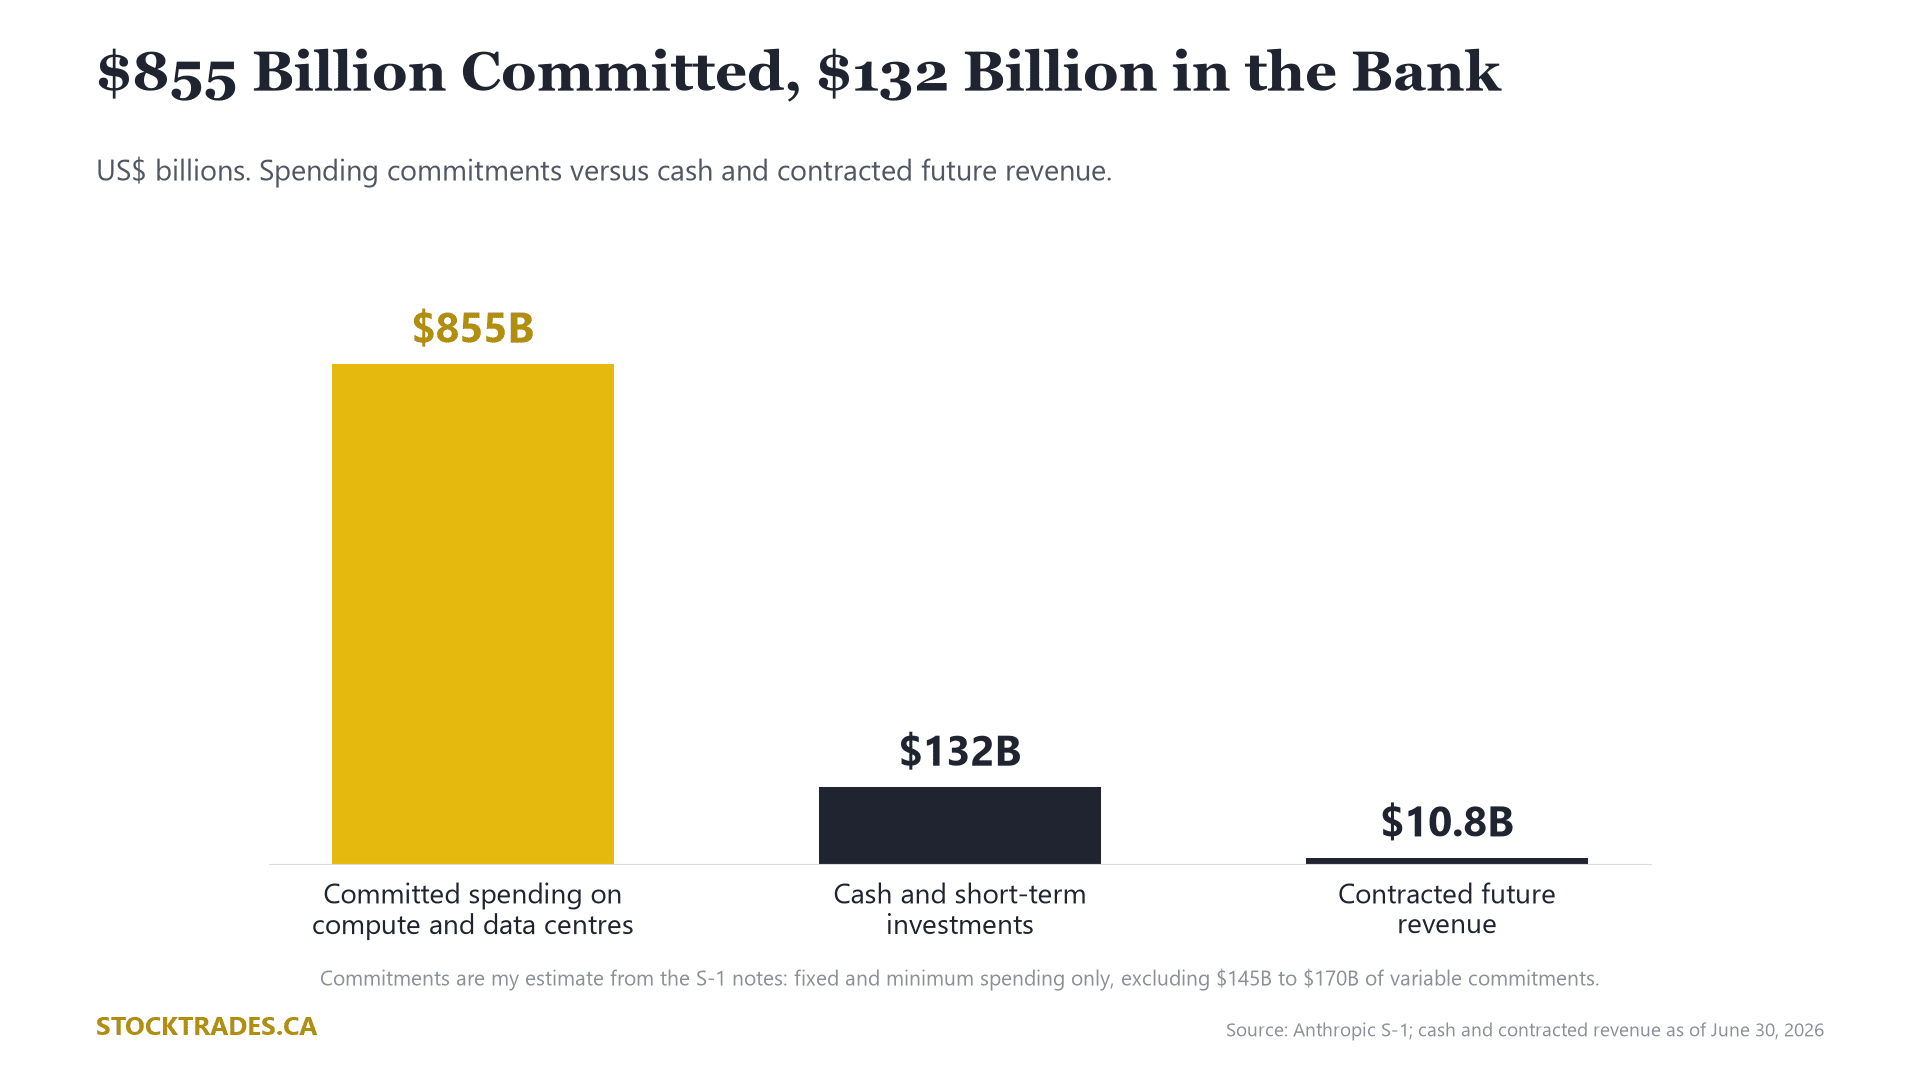
The individual agreements are worth paying attention to, particularly Broadcom’s (AVGO)
I want to make one thing absolutely clear. This single agreement with Broadcom took me over an hour to figure out, and it is a small fraction of the total complexities surrounding the business.
Broadcom sells Anthropic the chips. Then it offers Anthropic a loan of up to $42 billion to help pay the rent on those same chips. Then Broadcom will likely sell that loan to someone, another financial institution likely. It books the revenue, and mitigates the risk.
It is very similar to the car dealership model. You buy the car, the dealer arranges the financing, and then it often sells that loan to a bank. The dealer gets paid in full and the bank takes the risk.
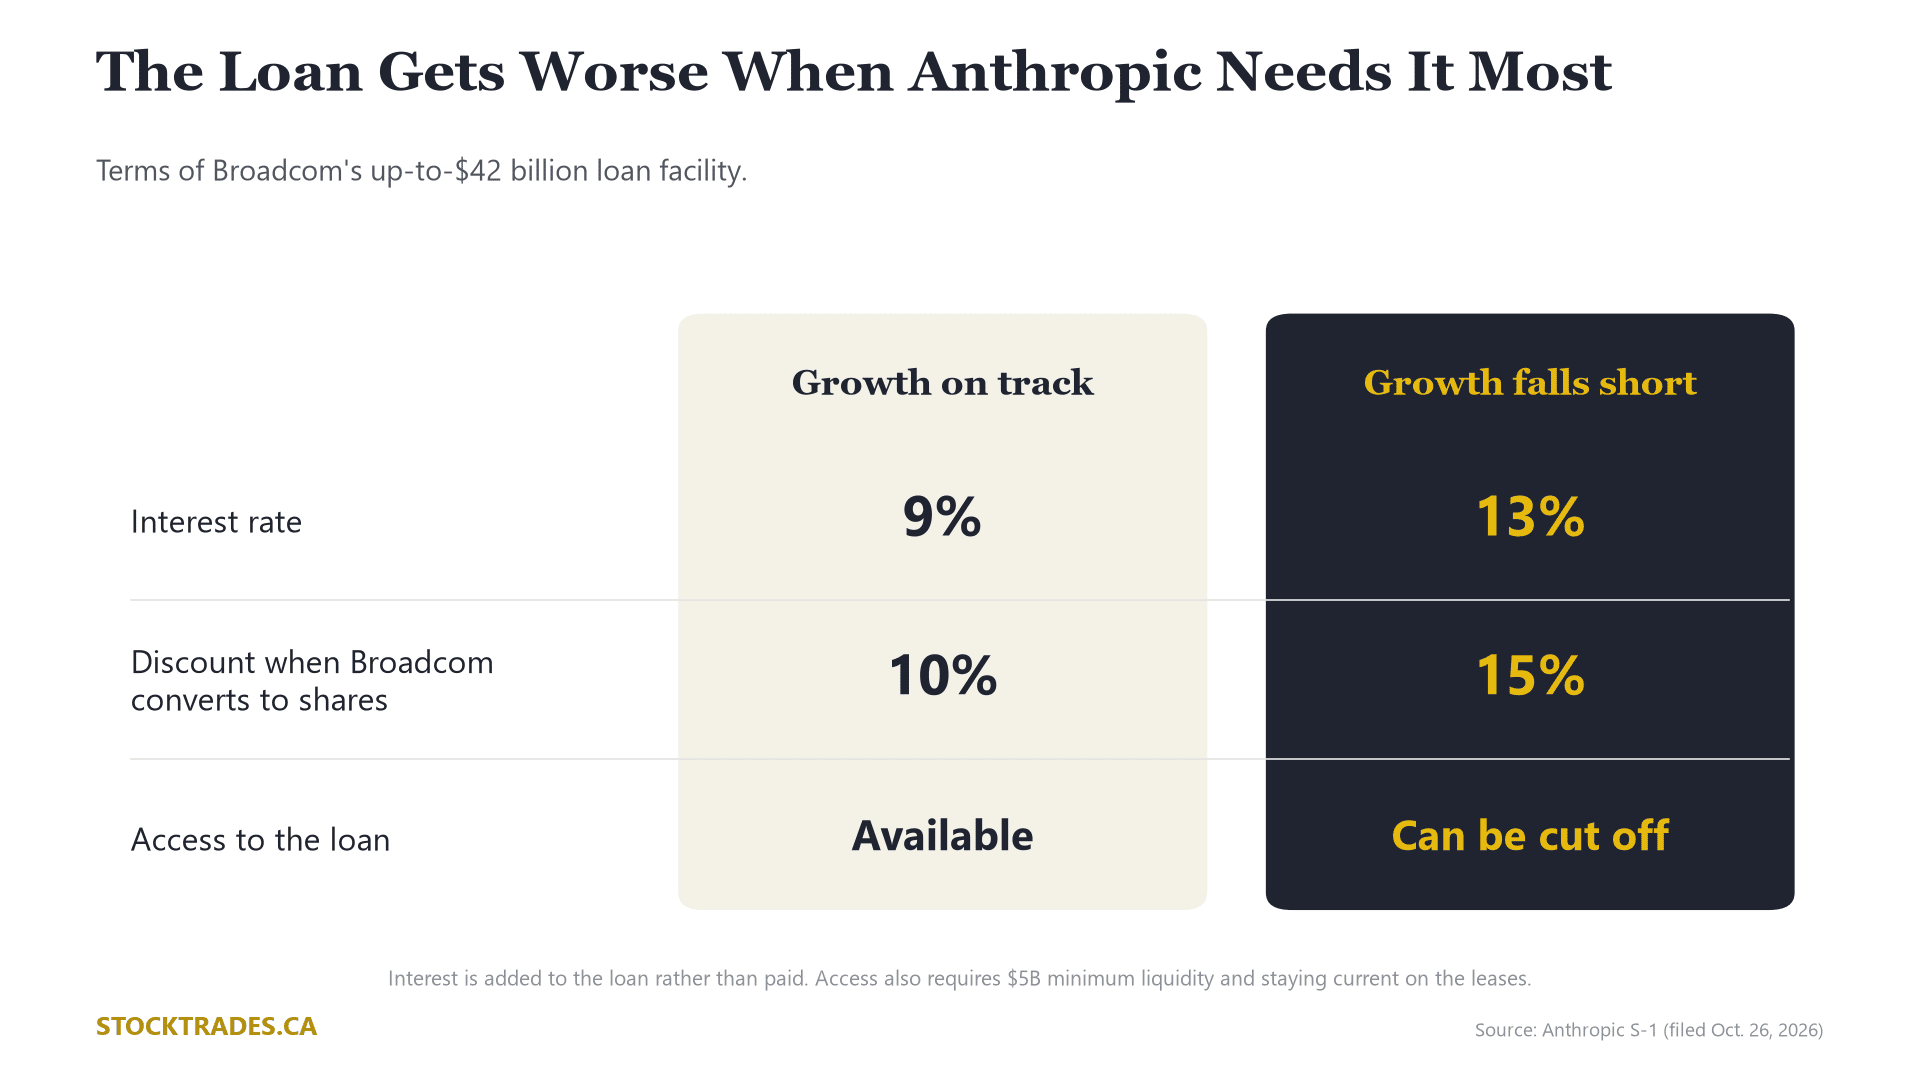
Broadcom can convert the loan into Anthropic shares at a 10% discount.
If Anthropic’s growth falls well short of certain targets, the discount rises to 15% and the interest rate rises to 13% from 9%.
If that happens for a sustained period, or Anthropic’s liquidity falls below $5 billion, Broadcom can cut off access to the loan.
Broadcom isn’t too worried about getting paid. If the money doesn’t come from Anthropic, it comes at the expense of public shareholders through dilution.
And the other thing is, this potential loan to Anthropic gets cut off when they’d potentially need the money the most.
__________
Let’s get into the earnings.
Alphabet (GOOGL)
Adjusted EPS was $2.67, up 22%. This was below expectations.
Revenue was $127.6 billion, up 25%. This was slightly below expectations.
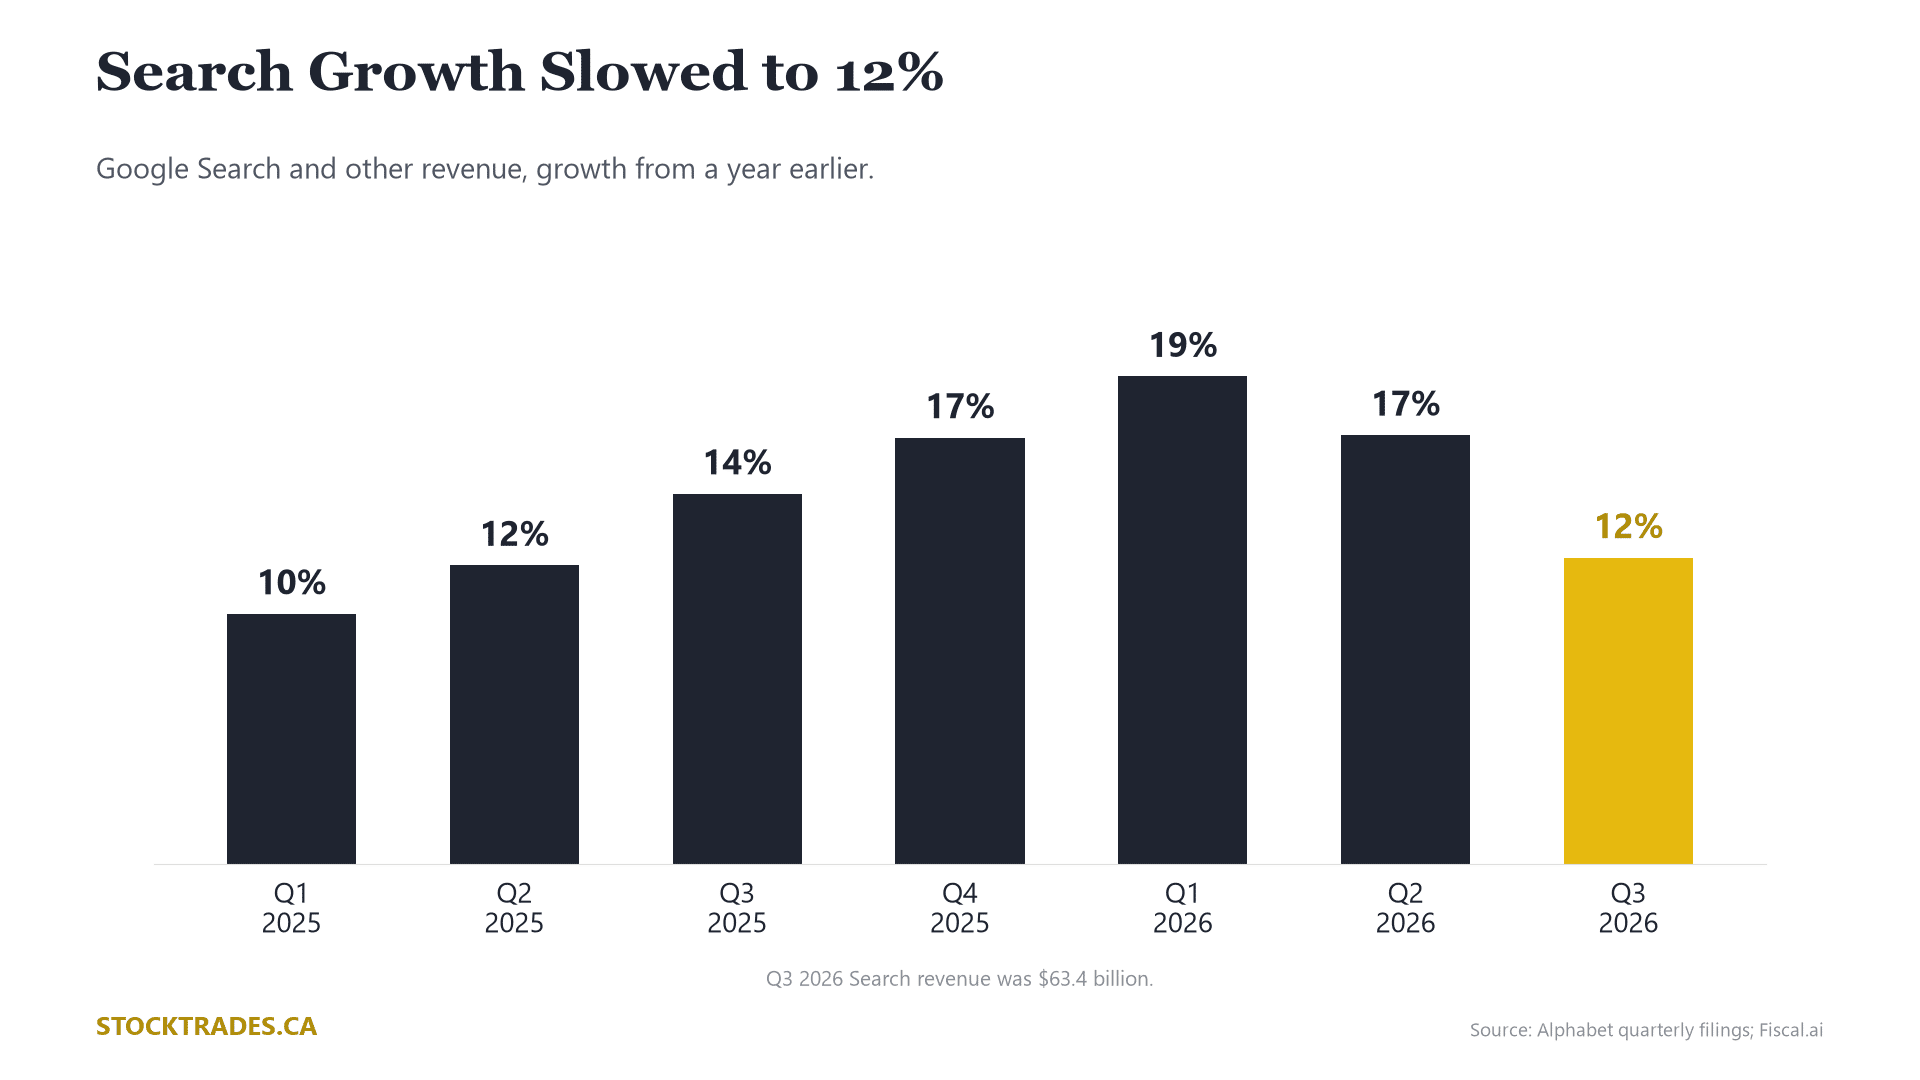
Search revenue increased 12% to $63.4 billion. That’s down from 19% growth in Q1 and 17% in Q2. I think this was the main cause of the dip post-earnings.
YouTube ad revenue rose 9%, also below expectations.
Google Cloud revenue rose 103% to $30.7 billion, above expectations. Its operating margin was 36%, up from 24% a year ago.
Cloud backlog reached $561 billion, up $47 billion in three months.
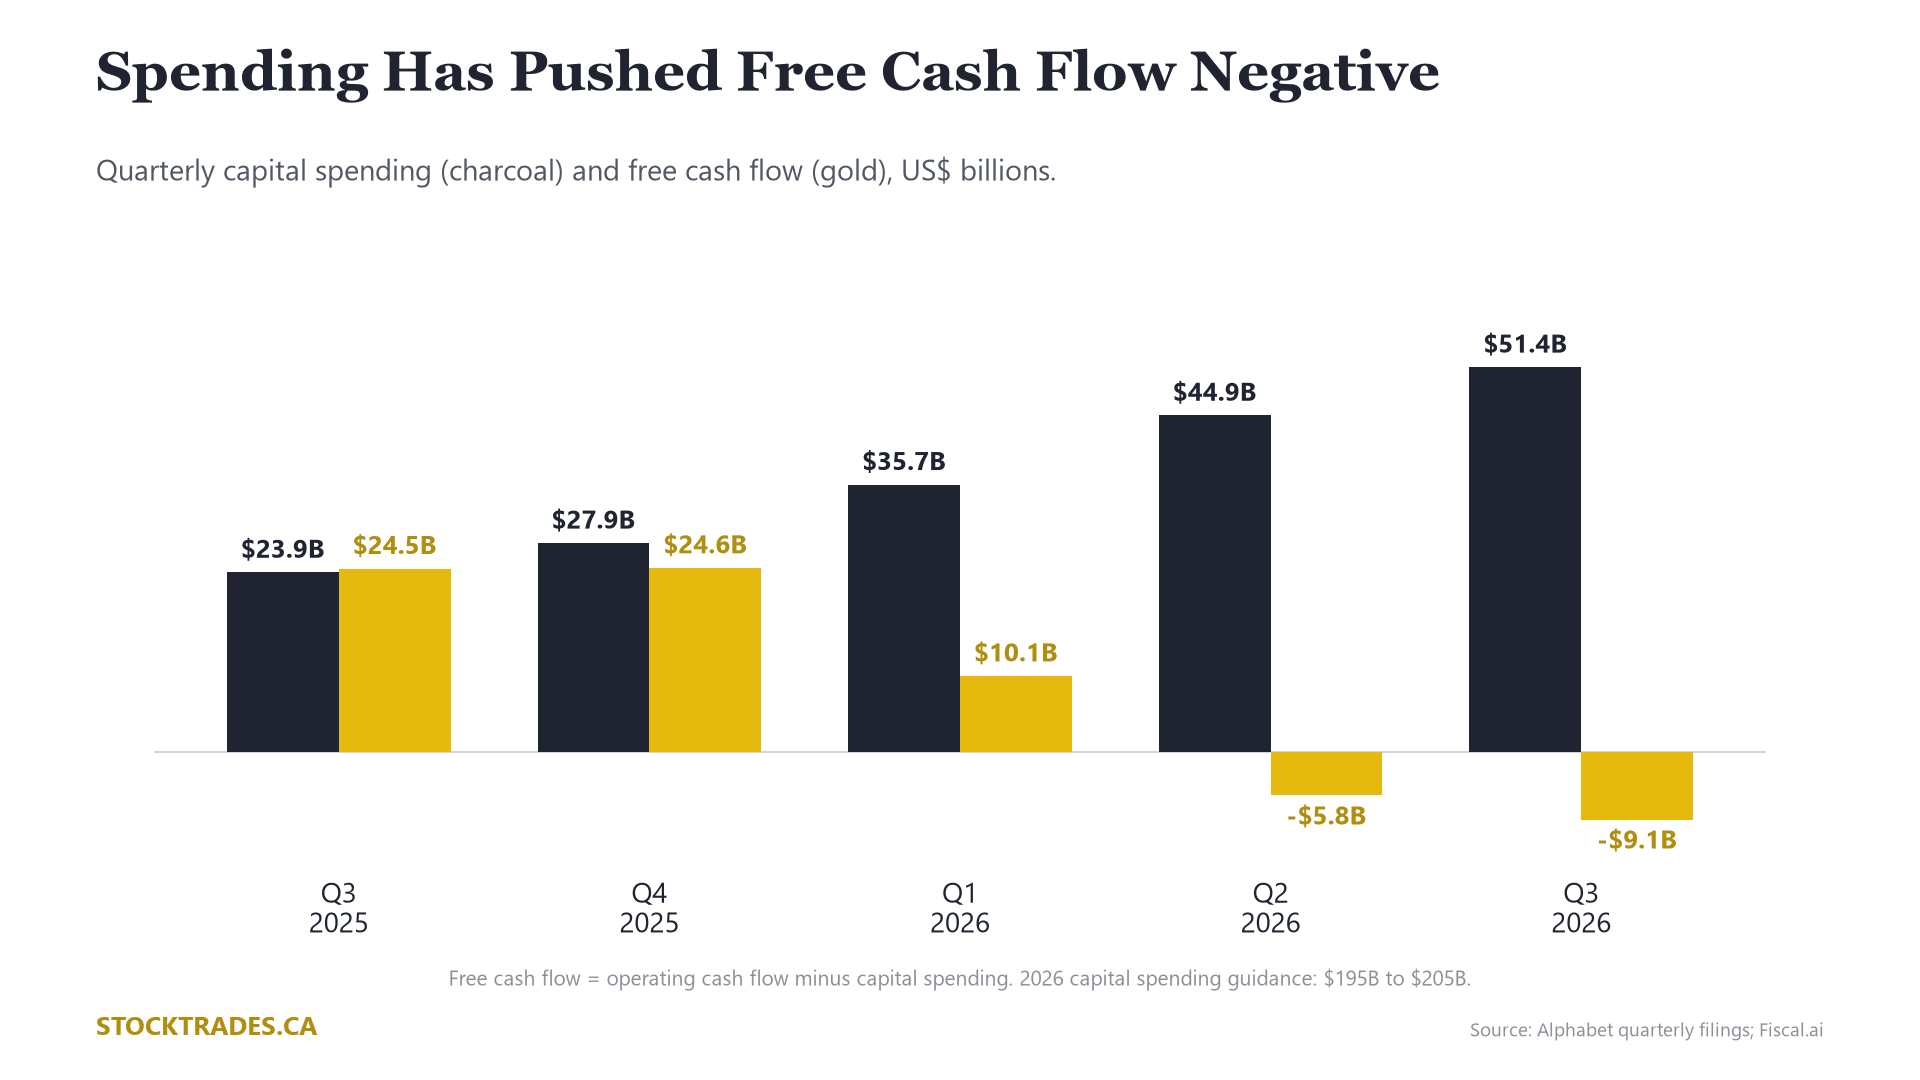
Capital spending was $51.4 billion, and free cash flow was negative $9.1 billion, the second negative quarter in a row. I wouldn’t expect any positive quarters for a while.
2026 capital spending guidance was maintained at $195-205 billion. Management expects 2027 to be “significantly” higher. The AI spend is not slowing down.
Do I think Alphabet had a good quarter? Not necessarily. Do I believe it was bad enough to send Alphabet to one of its worst single-day losses since its IPO? Absolutely not. Which is exactly why I added to my position on the drop.
Cloud is doing better than almost anyone expected, but the difficulty is Search is slowing.
We’re getting back to the main bear case when ChatGPT was launched. That Google’s golden goose, Google Search, was going to be disrupted.
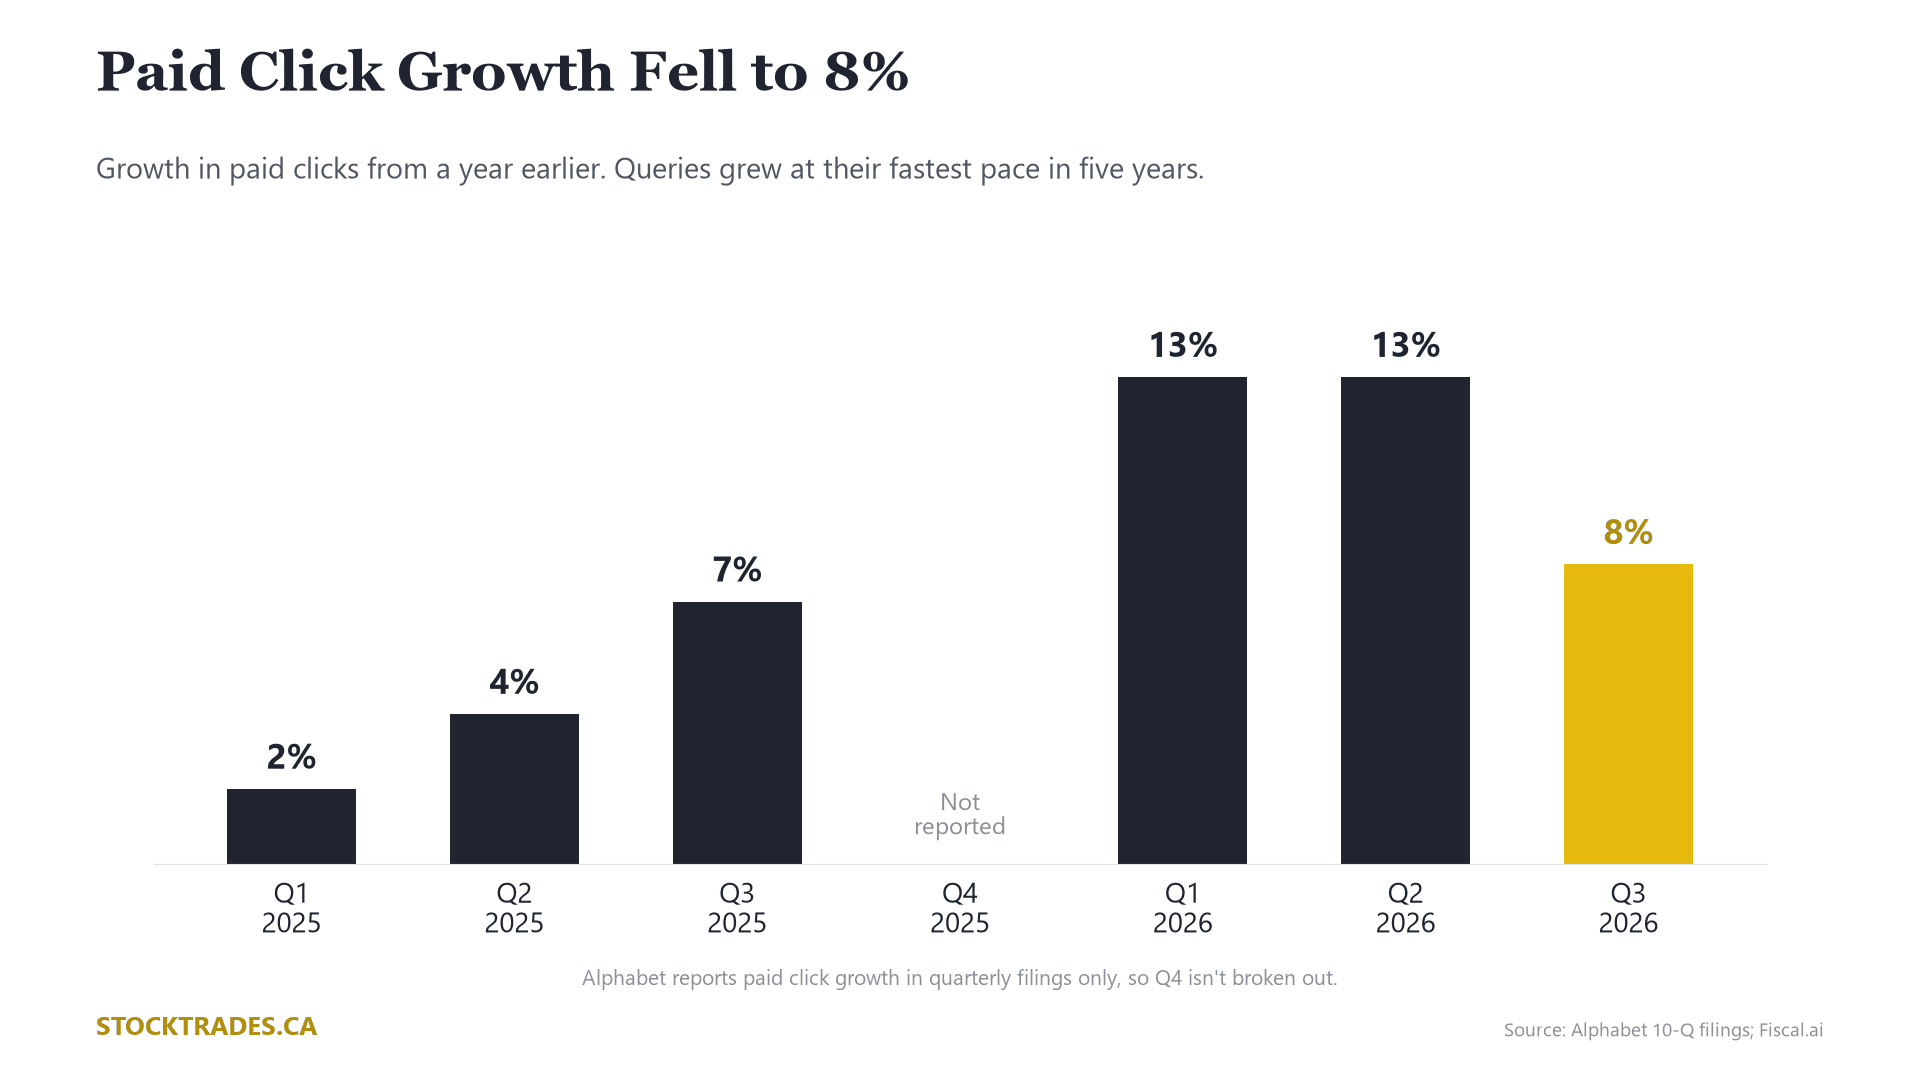
Search queries grew at their fastest pace in five years, but paid clicks increased only 8%. People are using Google more, but fewer of those searches are producing ad clicks.
A lot of the new usage is in AI Mode. Management admitted these searches don’t make as much money yet.
But the thing is, I wouldn’t assume that because AI Mode earns less per search today, it will always earn less. Alphabet has a way of making everything they touch exceptionally profitable.
Ads in AI Mode are only now starting to expand outside the US, and the company said ads in AI Mode are already getting clicked about as often as the regular product listings beside them. If those ads eventually perform, this double-digit dip in Alphabet’s share price will be a blip on the radar.
Cloud is the bright spot. Revenue doubled, profit more than tripled, and the $561 billion backlog is about six years of Cloud revenue, based on the last 12 months of sales. The best part? 55% of that backlog is expected to turn into revenue over the next couple of years.
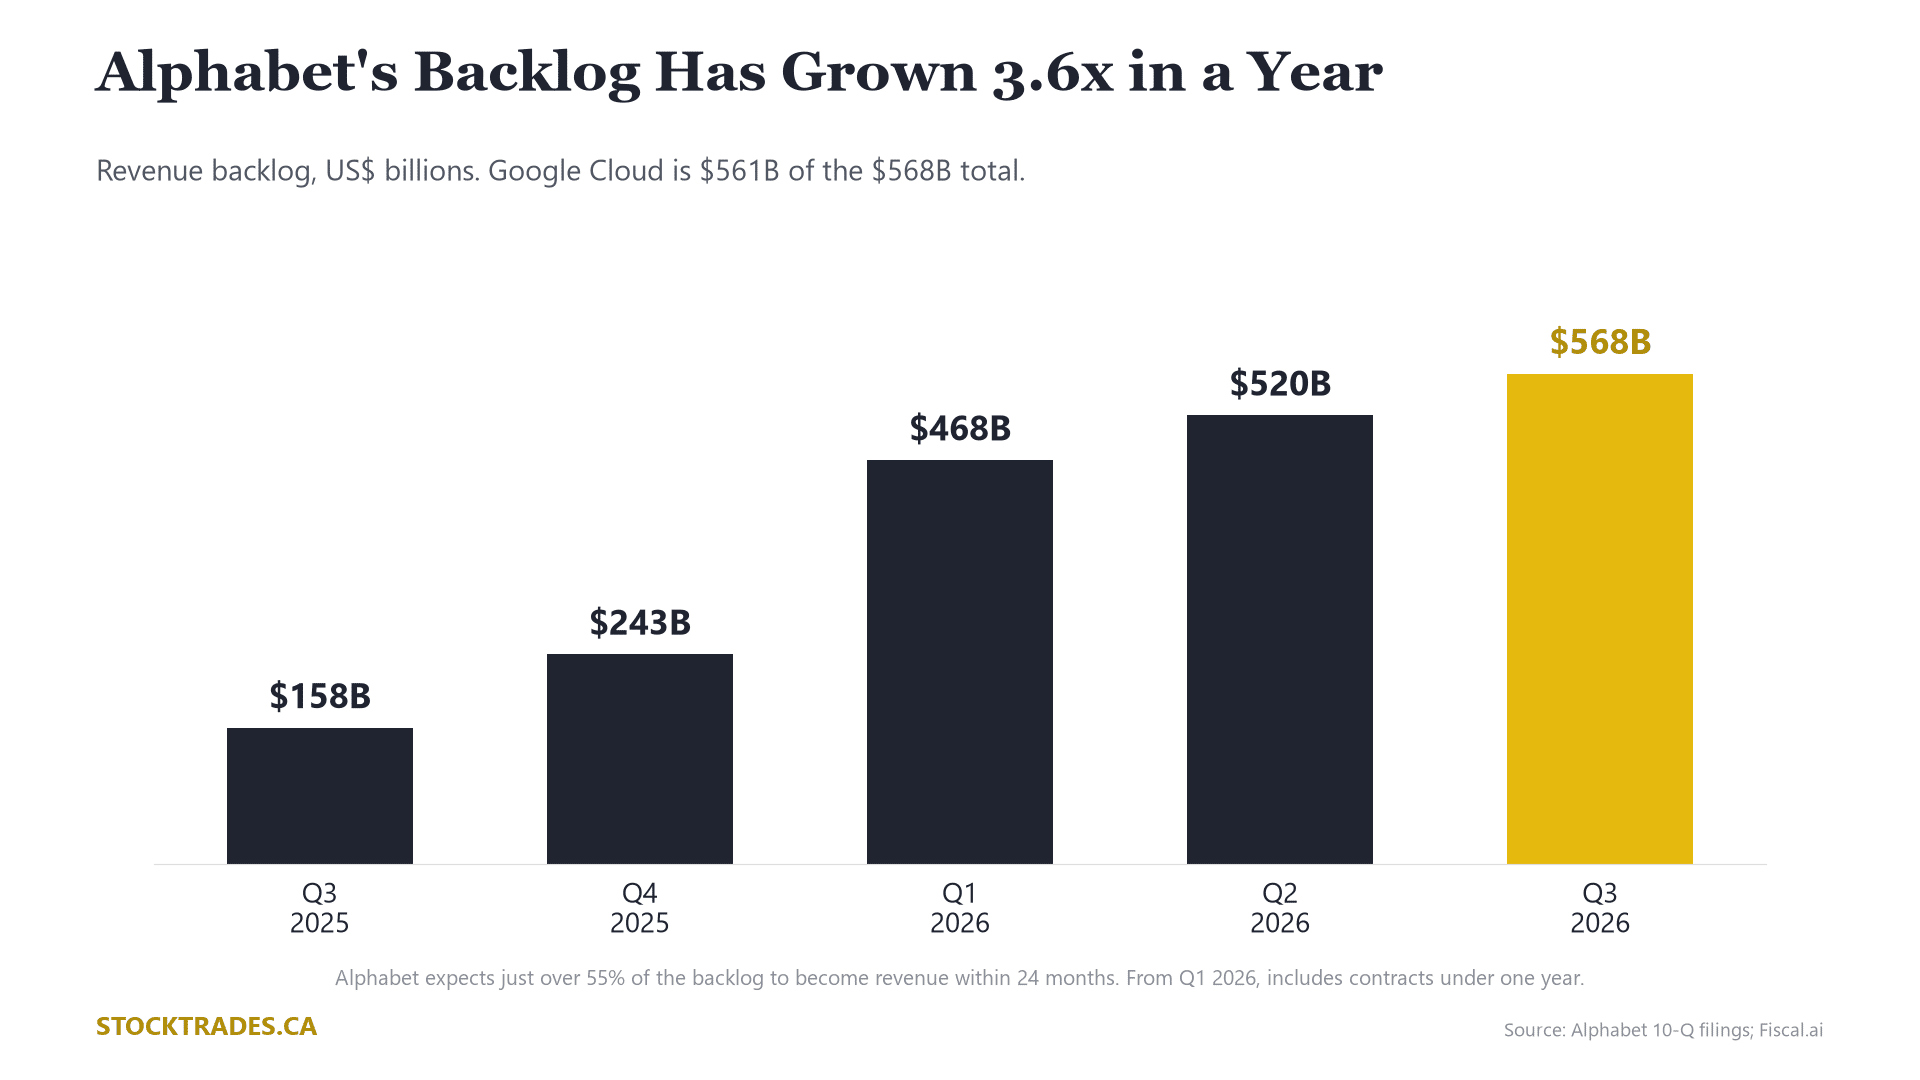
The spending is enormous. Operationally, I have few concerns with the business, even with the lagging Search results. It is the spending that concerns me.
Alphabet has spent $132 billion on capital projects so far this year. Free cash flow will likely be negative for the full year. Depreciation increased 49% this quarter and I have zero doubt that it will keep climbing for years.
This is one of the best management teams on the planet, in my opinion. Yes, the spending is a bit concerning, and the future profitability of that spending is up in the air. However, at some point we have to trust the management in place to deliver. This team has never really given me any reason to doubt.
I continue to hold, and as mentioned, I added on the weakness.

Comments
Log in or sign up to join the conversation.