
Analysts have hiked their revenue and price targets for Marvell Technology (MRVL) over the past two months. As a result, MRVL looks to be 32% too cheap at $308 per share. This article will discuss that.
This article will also review an interesting way to play MRVL: an out-of-the-money (OTM) put credit spread. I described this play in a prior Barchart article about a month ago, and it has worked well.
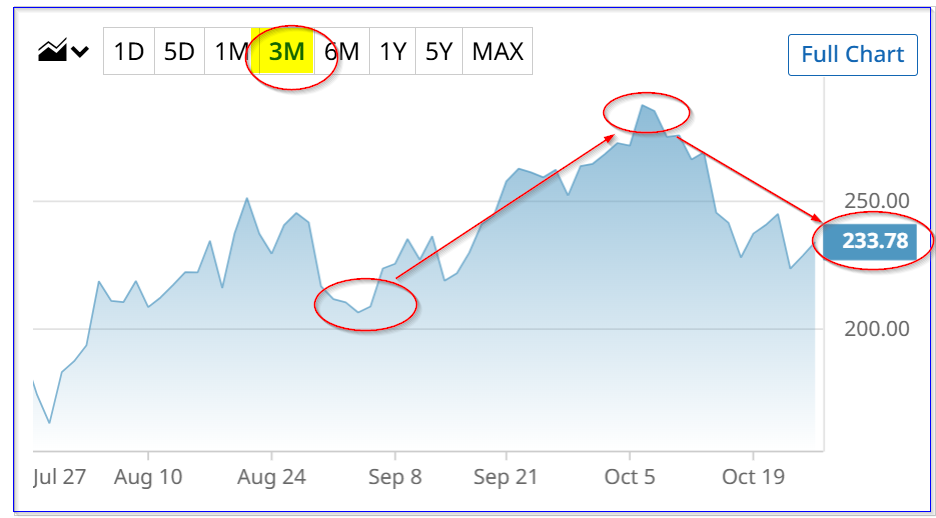
MRVL stock - past 3 months - Barchart - Oct. 26, 2026
MRVL closed at $233.68 per share on Monday, Oct. 26, up 2.3%. It has risen from a recent low of $218.82 on Sept. 14, but is well off its recent peak of $287.01 on Oct. 6.
Given how much analysts have raised their revenue forecasts, implying much higher free cash flow prospects, its underlying value increase could eventually push MRVL higher.
Here's why.
Higher Revenue, Free Cash Flow (FCF), and Price Target Forecasts
For example, analysts now project $19.71 billion for the 2027 fiscal year ending Jan. 2028. That's 8.18% up from $18.22 billion in a prior forecast, as seen in my Sept. 1, 2026, Barchart article ("Marvell Technology Posts Lower FCF Margins, But Revenue Is Could Surge Next Year - Is MRVL Stock Too Cheap?"). The company released its fiscal Q2 earnings on Aug. 27.
I pointed out that Marvell Technology's FCF margin for the prior 12 months was 18.3%. So, if the company keeps this up, it could generate $3.61 billion in FCF next year:
$19.71b revenue est. x 0.183 FCF margin = $3.607 billion FCF
As a result, its fair market value (FMV) is substantially higher. For example, using a 1.3% FCF yield metric, as in my last article, the FMV is:
$3.607b FCF est. /0.013 = $277.5 billion FMV
Compare that to its market cap of $210.1 billion today, according to Yahoo! Finance's calculation. It implies MRVL stock is worth 32% more:
$233.68 price x 1.32 = $308.46 per share
Other analysts have even higher price targets (PTs). For example, Yahoo! Finance's survey of 46 analysts is $341.44. That's up from $289.04, on Sept. 21, when I discussed MRVL's valuation in a Barchart article ("Marvell Technology Stock Price Targets Are Rising - What's the Best MRVL Play?"). Yahoo! Finance's PT is now 46% over Monday's closing price.
Similarly, Barchart's PT is now $337.05, up from $291.25 last month, and now it represents upside of 44.2%.
The bottom line is that MRVL stock looks deeply undervalued based on both its FCF forecasts and analysts' price targets.
One play I discussed in the Sept. 21 article is an out-of-the-money (OTM) put credit spread. That has worked well and can be repeated ahead of Marvell's expected Dec. 3 earnings release.
MRVL Put Credit Spread Play Performance
I discussed shorting the $215.00 put expiring Oct. 30 (41 days to expiry at the time), and simultaneously buying the $205.00 put to protect on the downside. The net premium collected was $275 (i.e., $838-$563).
However, just as important, the collateral required to do this play was only $1,000 (i.e., ($215 - $205) x 100). That is significantly lower than doing a short-put play at $215.00, which would have required $21,500 in collateral.
Today, that put credit spread has fallen to just $118 (i.e., $203-$85), as shown in Barchart's Oct. 30, 2026, 20 strike spread option chain link here.
So, the profit is:
$275 - $118 = $157 on $1,000 collateral required, or 15.7%
The at-risk return is even higher, as the spread is collected upfront, and the at-risk capital was just $725.
Note, however, the $118 profit was 42.9% of the total projected $275 profit.
It makes sense to repeat this play now, as it expires in 4 days. Anything can happen in the short term, so it makes sense to close it out and lock in the profits.
New MRVL Put Credit Spread Play
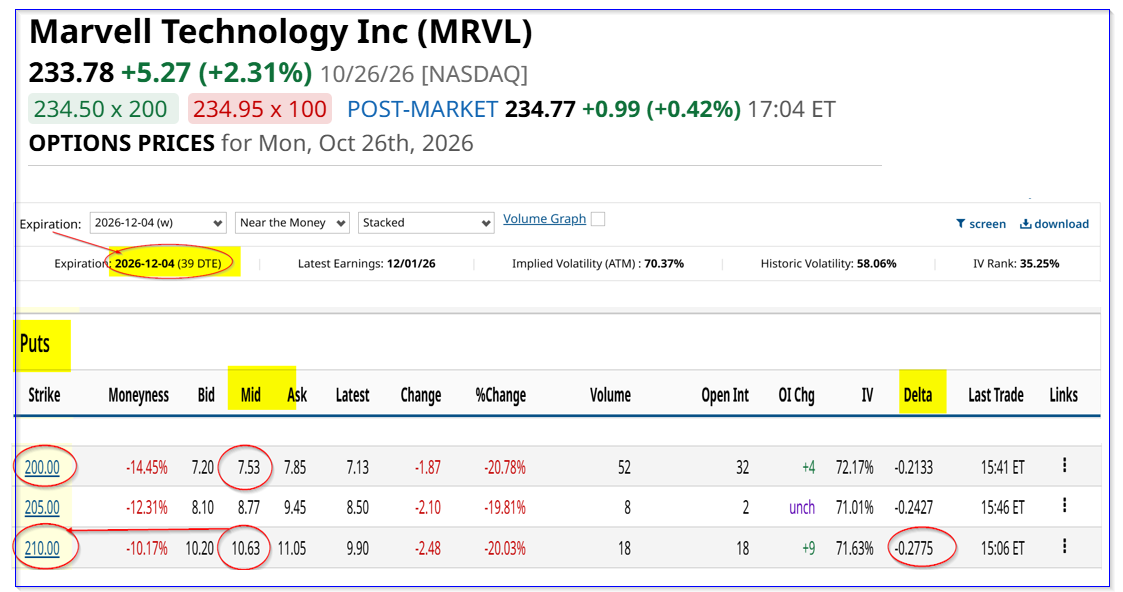
For example, look at the Dec. 4 expiration option chain (just after the expected Dec. 3 earnings release), 39 days to expiry.
It shows that the $210 put strike has a $10.63 midpoint premium, and the $200 strike is at $7.53. So, the net premium collected with $1,000 required collateral is $310 ($1,063-$753).
That represents a potential return of 31% (i.e., $310/$1,000). Moreover, from an at-risk standpoint, which may not reflect how it actually turns out, is higher:
$310 / ($1,000 - $310) = $310 / $690 = 44.9%.
For example, let's say the investor closes out this play at the 70% point - i.e., with 50% of the projected profit. The projected profit would be 15.5% of the collateral.
$310 x 0.50 = $155/$1,000 = 15.5% projected profit
However, the risk is that MRVL drops below $200. At that point, the at-risk amount ($1,000 - $310) of $690 is lost. The breakeven point for this spread is:
$210- $3.10 = $206.90 breakeven, or 11.5% below the Oct. 26 closing price ($233.68)
Below that point, down to $200.00, the investor begins to lose the at-risk capital.
However, the risk seems low, especially since the delta ratio is just -0.2775. That implies a 72% chance of success, where MRVL won't decline to $210 by Dec. 4.
Comments
Log in or sign up to join the conversation.