
The US equity indices closed higher on Thursday, offsetting losses from the previous two sessions. By the end of the day, the Dow Jones (US30) gained 0.61%. The S&P 500 (US500) rose 1.14%. The tech‑heavy Nasdaq (US100) finished up 1.73%. The key catalyst behind the rebound in risk appetite was the pullback in oil prices toward $100 per barrel following reports from Saudi Arabia about progress in repairing the East-West pipeline. The decline in energy prices eased investors’ fears of accelerating wholesale inflation and triggered a corrective retreat in US Treasury yields from multi‑year highs, immediately bringing buyers back into long‑duration assets.
In Europe, Thursday’s session ended with gains as well: Germany’s DAX (DE40) rose 0.70%, France’s CAC 40 (FR40) closed 0.57% higher, Spain’s IBEX 35 (ES35) added 1.00%, and the UK’s FTSE 100 (UK100) finished the trading day up 1.19%. The DAX 40’s move above 25,700 points demonstrated the European equity market’s ability to recover amid easing pressure from oil prices and bond yields. The correction in oil prices toward $100 per barrel reduces costs for Germany’s energy‑intensive industries. However, the medium‑term outlook for European indices is threatened by escalating tensions in international trade relations. Donald Trump’s threats to impose “very serious tariffs” on the European Union over Canada’s planned “associated membership” pose a direct risk to Germany’s export‑oriented economy.
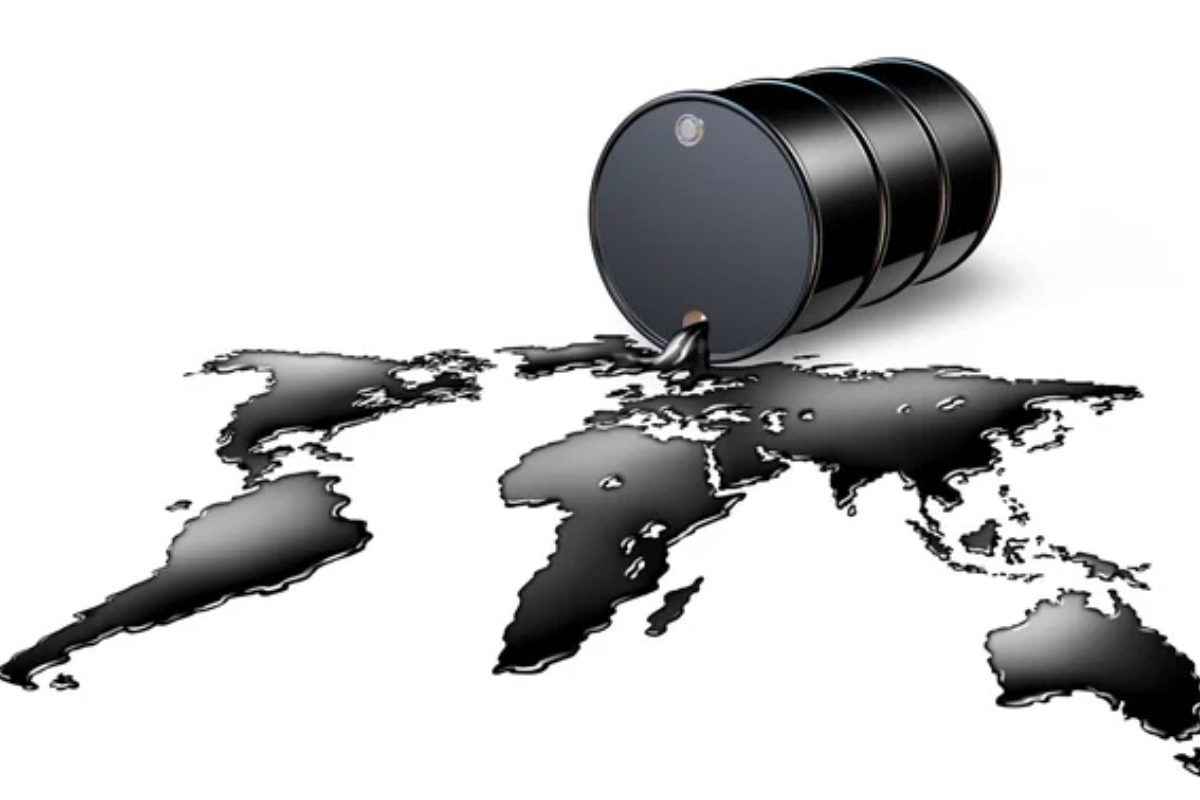
The drop in oil prices to $100 per barrel after a 3.2% decline the previous day reflects a temporary unwinding of the geopolitical risk premium in commodity contracts. Saudi Arabia’s statements about restoring roughly half of the damaged East-West pipeline’s capacity within days – and fully repairing it within six weeks – significantly eased fears of a prolonged physical supply shortage. An additional stabilizing factor was Riyadh’s prompt offer of alternative supply routes for Asian refineries. Despite the brief respite, the global energy market remains highly vulnerable to geopolitical risks. Persistent tensions around the Strait of Hormuz keep the world’s key hydrocarbon transit artery in a danger zone, preventing oil prices from entering a deeper correction.
The rise in US natural gas (XNG) prices to $2.92 per MMBtu reflects intensifying fundamental friction between domestic electricity demand and current supply dynamics. The latest EIA report recorded a weekly inventory build of 44 billion cubic feet – well below last year’s injection pace (87 bcf) and the five‑year average (74 bcf). As a result, total inventories of 3.298 trillion cubic feet remain 3.6% below last year’s level, while holding only a moderate 3.7% surplus over the five‑year norm.
In Asia on Friday, Japan’s Nikkei 225 (JP225) rose 0.33%, China’s FTSE China 50 closed 0.45% lower, Hong Kong’s Hang Seng (HK50) fell 0.44%, and Australia’s ASX 200 (AU200) finished 0.41% higher.
The New Zealand dollar’s (NZD) 1.6% weekly decline – its fourth consecutive weekly loss – was driven by the US Dollar Index holding near seven‑week highs after the Federal Reserve raised rates and signaled further tightening ahead. Meanwhile, New Zealand’s economic fundamentals continue to show resilience to external shocks. Q2 GDP growth of 0.2% quarter‑over‑quarter and 2.6% year‑over‑year exceeded both consensus expectations and the Reserve Bank of New Zealand’s own zero‑growth expectations, demonstrating the country’s ability to withstand the energy shock stemming from the US-Iran conflict.
The Bank of Japan’s September decision to raise the policy rate by 25 basis points to 1.25% marked a definitive departure from Tokyo’s long‑standing ultra‑loose monetary stance, pushing borrowing costs to a 31‑year high. The 7‑to‑2 vote split revealed growing divisions within the board.
The strengthening of the offshore yuan to 6.69 per dollar, the highest level since July 2022, highlighted the People’s Bank of China’s consistent strategy of managed currency appreciation. The eighth consecutive increase in the PBOC’s daily reference rate to 6.7521 per dollar marked the longest tightening streak in fixing since 2023. As a result, the PBOC’s steady fixing helps curb capital outflows and reduces the cost of raw material imports for the domestic economy.
S&P 500 (US500) 7,637.76 +85.95 (+1.14%)
Dow Jones (US30) 51,778.04 +316.14 (+0.61%)
DAX (DE40) 25,716.71 +178.96 (+0.70%)
FTSE 100 (UK100) 10,816.14 +127.67 (+1.19%)
USD Index 100.25 -0.01 (-0.01%)
News feed for: 2026.09.18
New Zealand Trade Balance (q/q) at 01:45 (GMT+3) – NZD (MED)
Japan National Core Consumer Price Index (m/m) at 02:30 (GMT+3) – JPY (HIGH)
Japan BoJ Outlook Report at 06:00 (GMT+3) – JPY, JP225 (HIGH)
Japan BoJ Interest Rate Decision at 06:00 (GMT+3) – JPY, JP225 (HIGH)
UK Retail Sales (m/m) at 09:00 (GMT+3) – GBP (MED)
US Industrial Production (m/m) at 16:15 (GMT+3) – USD (MED)
Comments
Log in or sign up to join the conversation.