
We've taken a couple of looks at the Northern Trust 2055 Inflation-Linked Distributing Ladder ETF (TIPD). The example we came up with for a use case was to cover property tax for most or all of retirement. Our property tax in Walker is about $2000 so $60,000 in TIPD should cover it. The inflation rate for things like Medicare or homeowners insurance typically exceeds the inflation rate used to adjust TIPS.
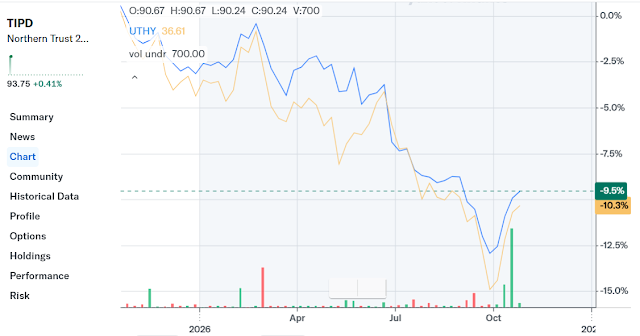
The chart compares TIPD with UTHY, which tracks 30-year Treasury bonds. TIPD bottomed out with a 12.5% drawdown on a price basis and is currently down 9.5%. It has a holding maturing in December, which will be the big payout for the year. The duration of the fund will slowly go down as we move closer to 2055, but it will be sensitive to interest rates for many more years. For a little context, TIPA, which is the Northern Trust fund maturing in 2030, is down a little less than 2%.
Everything is working as it should, but when we work on some of these ideas (theories), they are always interesting, but it is important to check in on what actually owning, in this case TIPD to cover 30 years of property tax, is really like.
If someone can devote $60,000 or maybe a higher amount for a more expensive county to such a narrow purpose, then maybe it makes sense, but it will be volatile. I would not devote 10% of my nest egg for long-term property tax coverage, but 5% might be reasonable.
Clearly, TIPD would be a source of volatility, repeated for emphasis.
Comments
Log in or sign up to join the conversation.