
If your credit score has a few minor dings — or maybe some major dents — then be assured that you certainly aren’t alone.
In fact, research has found that nearly one-third of adults in the U.S. have what is categorized as “impaired credit”; which is a nicer way to say that they don’t qualify for funding from prime lenders (like banks), and must either work with secondary lenders and pay substantially more to borrow — or in some cases, they can’t get funding at all. And we aren’t talking about credit to pay for a family vacation on the Disney Cruise. We’re talking money to pay for essentials like home and vehicle repairs, or to keep their small business afloat and from going under.
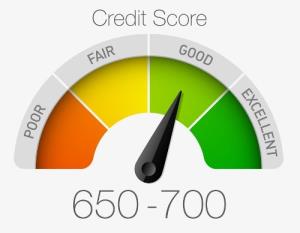
So yes, having bad credit is more than frustrating: it’s risky, because it limits options and drives up costs. But this situation doesn’t and shouldn’t be permanent. To that end, here are three proven and practical ways to improve your credit score:
1. Reign in your spending.
Before you start figuring out what to do with additional cash (and we’ll get to that in a moment), start by doing a gut check and discovering why your credit is low in the first place. If necessary, work with a reputable life coach who understands — sometimes better than financial coaches — that poor spending habits are often rooted in sub-optimal (read: bad) lifestyle choices. That means changing how you live and what you do, will have a positive impact on how much you spend — and ultimately, how much you keep.
2. Get your credit score from all bureaus.
A credit score is just a number. What comprises that number, however, is what really matters. To that end, get your credit score from all bureaus and scrutinize each one to see what’s pulling your credit score down. You may discover old mistakes that you assumed had cleared up, but have not yet been reported. There may also be old debts that are on the books, that could be wiped out if you make a reasonable offer to creditors.
3. Take out a loan with an alternative lending company.
Since your credit isn’t good (at the moment!), applying for a conventional bank loan is a waste of time. Instead, it makes more sense to take out a loan from an alternative lending company that caters to impaired credit borrowers. As you pay back the loan, the lending company will update the credit bureaus — and your credit score will slowly but surely rise. And just as importantly: while banks can take months to assess (and often reject) an application, alternative lenders specialize in fast business loans that can go from application to funding within a week.
The Bottom Line
Living with bad credit doesn’t have to be a permanent punishment: it can and should be a temporary situation. The above tips will help you repair your credit profile (or overhaul it if need be), so that you head towards good credit territory where prime lenders compete for your business, and you have the leverage. Doesn’t that have a nice ring to it?
Comments
Log in or sign up to join the conversation.